Equity settled share-based payments account for the payment for goods/services in the form of equity instruments (shares or share options) of the company or group company.
Last Updated – September, 2026
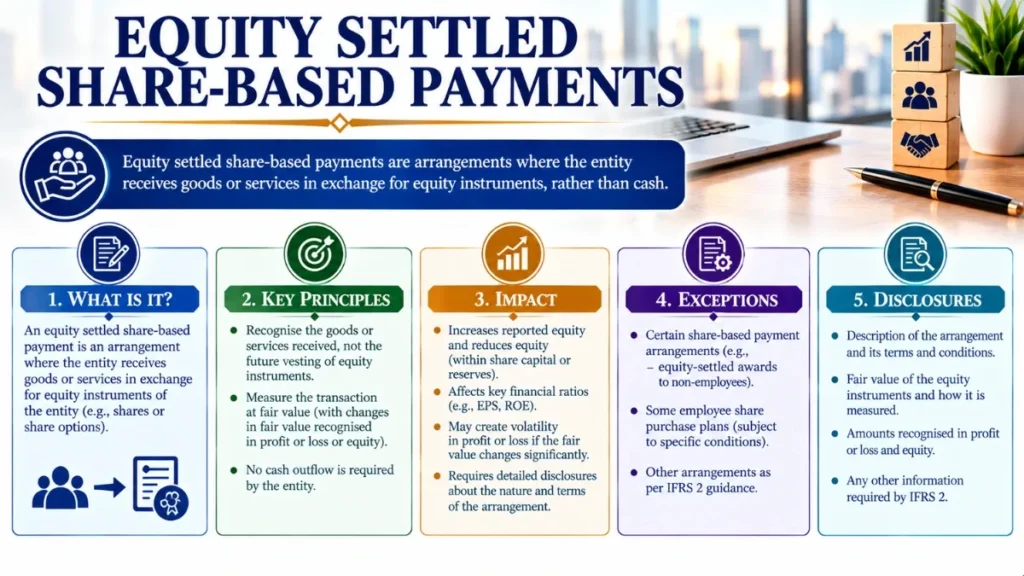
Equity Settled
Share-based Payments
01 · OVERVIEWWhat Are Equity Settled Share-based Payments?
Equity Settled Share-based Payment is a transaction in which an entity receives goods or services as consideration for its own equity instruments (including shares, share options, or other equity instruments). The entity settles its obligation by issuing equity rather than paying cash.
These arrangements are present in modern corporate compensation, from startup stock option plans to FTSE 100 long-term incentive programmes (LTIPs). Understanding their accounting treatment under IFRS 2 – Share-based Payment ( IASB official standard ) is essential for accountants, CFOs, auditors, and investors alike.
The date on which the entity and counterparty agree to the arrangement and fair value is measured.
Shares, share options, or instruments that give the holder a residual interest in the entity.
Measured at grant date; not remeasured subsequently, the key difference from cash settled share-based payments.
The period over which all specified vesting conditions must be satisfied by the counterparty.
02 · SCOPEWhen Does IFRS 2 Apply?
IFRS 2 applies to all share-based payment transactions, whether with employees or other parties supplying goods or services. It covers three broad categories of arrangements:
- Employee share option schemes
- Restricted stock unit (RSU) plans
- Long-term incentive plans (LTIPs)
- Save-As-You-Earn (SAYE) schemes
- Share purchase plans
- Goods/services settled by issuing equity
- Group share-based arrangements
03 · RECOGNITIONRecognition Principles
Under IFRS 2, when an entity grants equity instruments to employees, it recognises a corresponding increase in equity. The expense is spread over the vesting period as the employee renders service, reflecting the economic substance of the arrangement.
The Core Accounting Entry
Debit: Employee Benefit Expense (P&L) or the relevant cost (e.g., inventory, fixed asset)
Credit: Equity Reserve (Share-based Payment Reserve in equity)
The expense is recognised over the vesting period as the services are received from the employee.
Transactions with Employees vs Non-employees
For employee transactions, the fair value of services cannot be reliably estimated directly, so the fair value of the equity instruments granted is used as a proxy, measured at grant date and fixed thereafter.
For non-employee transactions, the fair value of goods or services received is measured directly, with the equity instruments’ fair value used only if the direct measure is unreliable.
Key principle: The total expense recognised over the full vesting period equals the fair value of equity instruments that ultimately vest, adjusted for any market conditions baked into the grant-date fair value.
04 · MEASUREMENTHow Are Equity Settled Share-based Payments Measured?
The fair value of equity instruments, particularly share options is determined at grant date using an appropriate option-pricing model. IFRS 2 does not prescribe a specific model but acknowledges the following approaches:
| Model | Best Used For | Key Inputs |
|---|---|---|
| Black-Scholes-Merton | European-style options; simple plans | Spot price, exercise price, volatility, risk-free rate, dividend yield, time to expiry |
| Binomial Lattice | American-style options; early exercise likely | Same as BSM plus expected early exercise patterns |
| Monte Carlo Simulation | Market-based conditions (TSR, relative performance) | Correlated share price paths, market conditions |
| Intrinsic Value | Permitted only if fair value cannot be estimated reliably | Spot price minus exercise price (minimum floor) |
Key Inputs & Considerations
| Input | Estimation Guidance |
|---|---|
| Share Price | Market price of shares at grant date |
| Exercise Price | Set in the option award terms |
| Expected Volatility | Historical volatility of entity’s shares; implied volatility if observable |
| Expected Life | Weighted average period options are expected to be outstanding (typically shorter than contractual term) |
| Risk-Free Rate | Yield on zero-coupon government bonds with term matching expected option life |
| Expected Dividends | Excluded from fair value if option holder does not receive dividends during the vesting period |
05 · VESTINGVesting Conditions Explained
Vesting conditions determine whether and when the counterparty becomes entitled to the equity instruments. IFRS 2 classifies conditions into two types, each attracting a fundamentally different accounting treatment:
- Linked to market price of entity’s shares (e.g., Total Shareholder Return vs. index)
- Probability of achievement incorporated into grant-date fair value via Monte Carlo
- Expense recognised regardless of whether condition is met
- No true-up adjustment for market condition outcomes
- Service conditions (e.g., continuing employment for 3 years)
- Performance conditions (e.g., EPS growth, revenue targets)
- NOT reflected in grant-date fair value
- Expense based on best estimate of instruments expected to vest
- True-up required at each reporting period end
The Vesting Timeline
Grant Date
Entity and counterparty agree to the arrangement. Fair value of equity instruments is determined. Vesting period commences.
During Vesting Period
Expense recognised on a straight-line basis (or accelerated for graded vesting). Estimate of instruments expected to vest updated at each period end.
Vesting Date
Cumulative expense equals: number of instruments actually vested × grant-date fair value. Equity reserve is not subsequently remeasured.
Exercise Date (Options)
Share-based payment reserve transferred to share capital and share premium. Cash received for exercise price (if any) also credited.
Lapse / Forfeiture
If options lapse unexercised post-vesting, the reserve may be transferred to retained earnings, no reversal of P&L expense is permitted.
06 · MODIFICATIONSModifications, Cancellations & Settlements of Equity Settled Share-based Payments
Entities sometimes modify the terms of share-based payment awards during the vesting period, for example, reducing the exercise price following a share price fall. IFRS 2 provides specific guidance on each scenario:
| Event | Accounting Treatment |
|---|---|
| Beneficial Modification (e.g., reduced exercise price) | Recognise incremental fair value (modified FV minus original FV) over remaining vesting period, in addition to original grant-date FV |
| Non-beneficial Modification | Ignore the modification; continue accruing based on original grant-date FV as if no change occurred |
| Cancellation or Settlement (during vesting period) | Accelerate recognition of remaining unvested expense immediately; any payment up to grant-date FV charged to equity; excess charged to P&L |
| Replacement Awards (e.g., in restructurings) | Treated as a modification; incremental FV recognised over remaining vesting period |
| Post-vesting Cancellation | No P&L effect; equity reserve may be transferred to retained earnings within equity |
Cancellation rule: When an entity cancels an award during the vesting period, the unvested expense must be accelerated and recognised immediately. IFRS 2 treats cancellation as if vesting had occurred on the date of cancellation.
07 · JOURNAL ENTRIESJournal Entries & Examples of Equity Settled Share-based Payments
Example Setup
On 1 January 20X1, an entity grants 1,000 share options to an employee, with an exercise price of £5 per option. Grant-date fair value = £3 per option. Vesting condition: 3 years’ continuous service. All options vest and are exercised on 31 December 20X3.
Annual expense = (1,000 × £3) ÷ 3 years = £1,000 per year
| Dr Employee Benefit Expense (P&L) | £1,000 |
| Cr Share-based Payment Reserve (Equity) | £1,000 |
| Dr Employee Benefit Expense (P&L) | £1,000 |
| Cr Share-based Payment Reserve (Equity) | £1,000 |
| Dr Cash | £5,000 |
| Dr Share-based Payment Reserve (Equity) | £3,000 |
| Cr Share Capital + Share Premium | £8,000 |
Note: If options lapse unexercised after vesting, the £3,000 reserve is simply reclassified within equity to retained earnings, no reversal of the P&L expense is permitted under IFRS 2.
Forfeiture Adjustment Example
If at Year 2 the entity revises its estimate downward expecting only 800 options to vest due to staff leavers, the cumulative expense is recalculated:
08 · DISCLOSUREDisclosure Requirements
IFRS 2 requires extensive disclosures enabling users of financial statements to understand the nature, extent, and financial effects of share-based payment arrangements in existence during the reporting period.
Nature & Extent Disclosures
- Description of each type of share-based payment arrangement in existence during the period
- Number and weighted average exercise price of options outstanding at start and end of period, granted, forfeited, exercised, and expired
- Weighted average share price at date of exercise for options exercised during the period
- Range of exercise prices and weighted average remaining contractual life of outstanding options
Fair Value Determination Disclosures
- Weighted average fair value of options granted and information on how fair value was measured
- Option pricing model used and its inputs (exercise price, share price, expected volatility, option life, dividends, risk-free rate)
- How expected volatility was determined and whether it is based on historical volatility
- Any other features of the option grant incorporated into fair value measurement (e.g., market conditions)
Effect on P&L and Balance Sheet
- Total expense recognised in the income statement from share-based payment transactions
- Total carrying amount in equity (share-based payment reserve) at period end
- Liabilities arising from cash-settled share-based arrangements (if any)
09 · FAQFrequently Asked Questions
What is the key difference between equity-settled and cash-settled share-based payments?
Is the expense reversed if options are forfeited due to non-market performance conditions?
Can a company use intrinsic value instead of fair value?
How does graded vesting differ from cliff vesting for expense recognition?
What happens to the share-based payment reserve when options lapse after vesting?
How are group share-based payment arrangements accounted for?
(Qualified) Chartered Accountant – ICAP
Master of Commerce – HEC, Pakistan
Bachelor of Accounting (Honours) – AeU, Malaysia