SIC-32 Intangible Assets – Website Costs

SIC-32

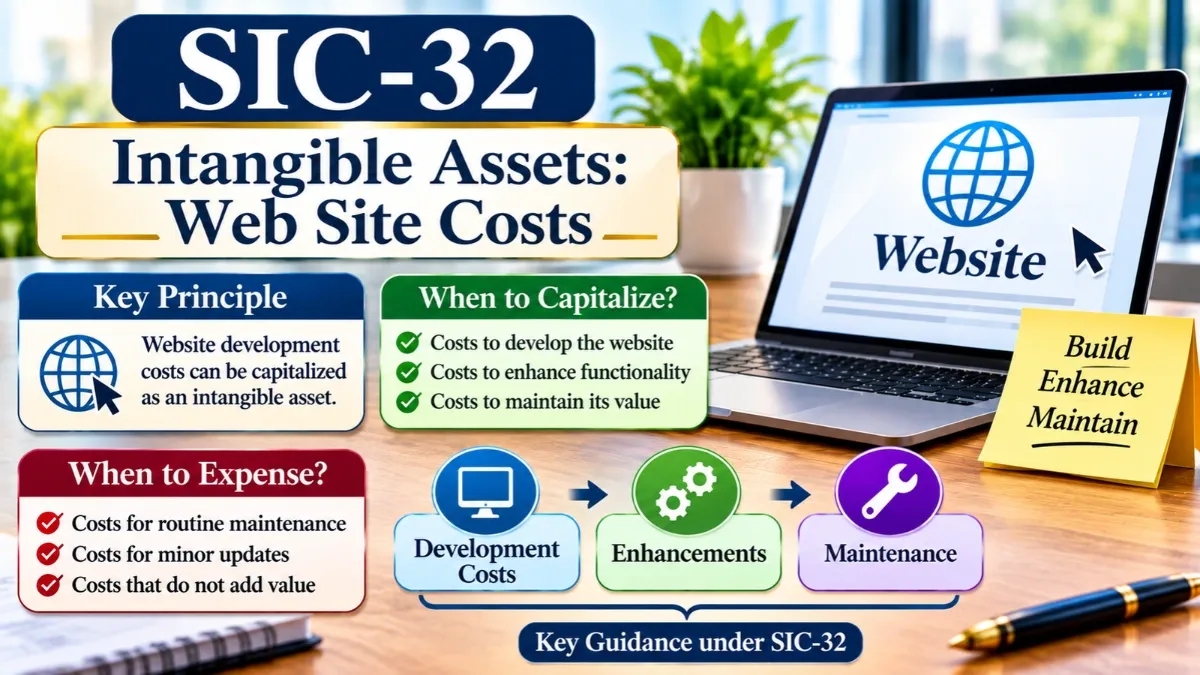
SIC-32 Intangible Assets – Website Costs explains how expenditure incurred on developing and maintaining a website should be accounted for under IFRS. It provides guidance on when website development costs can be recognised as an intangible asset and when they must be expensed as incurred. The interpretation applies the recognition … Read More

Assets Vs Liabilities – Key Differences and Examples

Assets Vs Liabilities

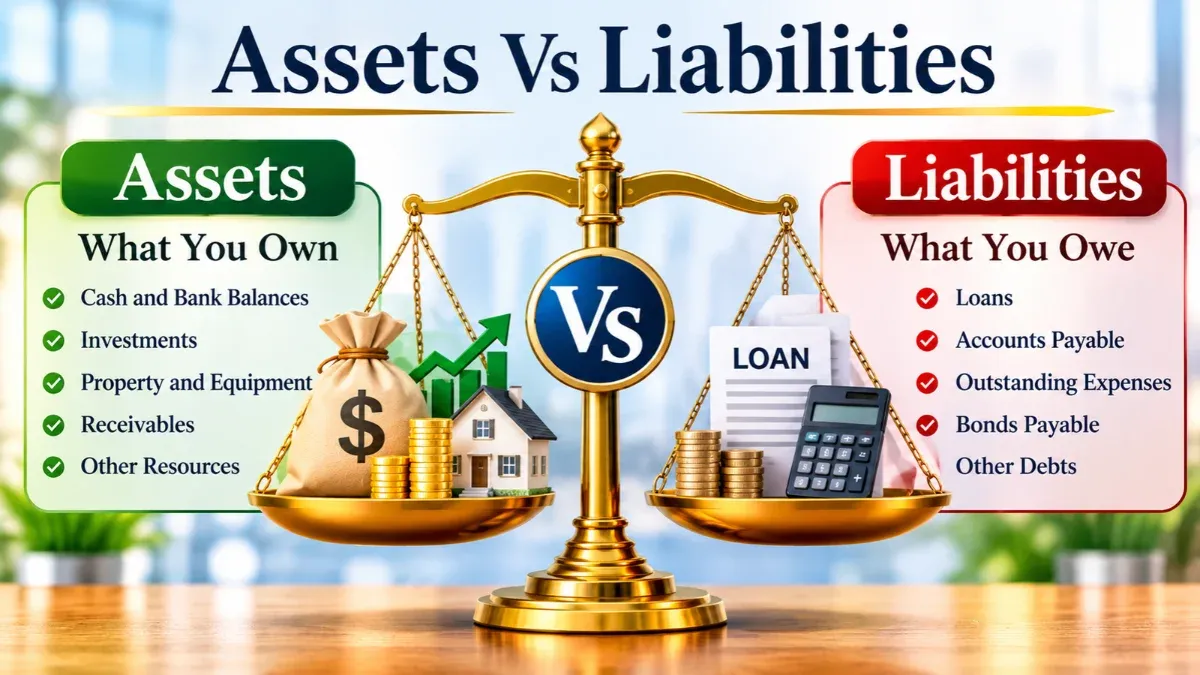
Assets vs liabilities are two fundamental components of accounting that help individuals and businesses understand their financial position. Assets are resources owned or controlled that provide future economic benefits, such as cash, property, inventory, and equipment, whereas liabilities are financial obligations owed to others, including loans, accounts payable, and outstanding … Read More

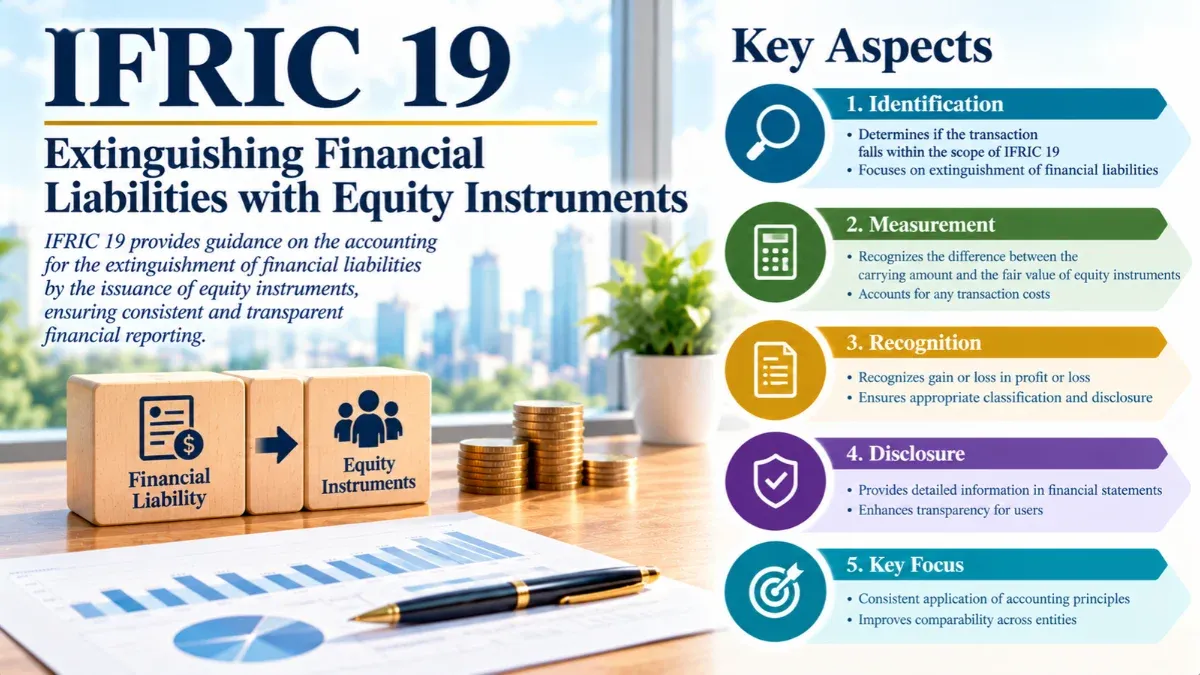
IFRIC 19 – Extinguishing Financial Liabilities with Equity Instruments

IFRIC 19

IFRIC 19 – Extinguishing Financial Liabilities with Equity Instruments states that the derecognition of financial liabilities takes place when it is extinguished i.e. when the obligation specified in the contract is discharged or canceled or expired. Last Updated – October, 2026 IFRS Interpretations • Financial Instruments IFRIC 19 – Extinguishing … Read More

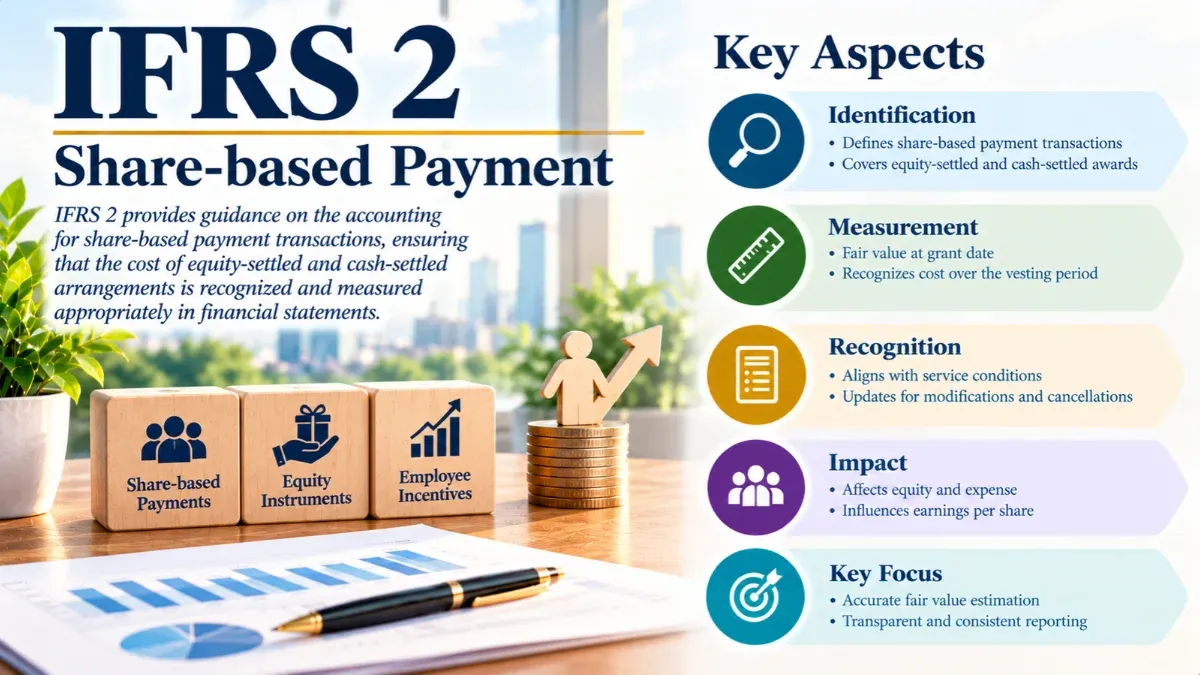
IFRS 2 – Share-based Payment

IFRS 2

The objective of IFRS 2 – Share-based Payment is to specify the financial reporting by an entity when it undertakes a share‑based payment transaction. In particular, it requires an entity to reflect in its profit or loss and financial position the effects of share‑based payment transactions, including expenses associated with … Read More

IFRS Vs US GAAP – Key Differences, Similarities & Examples

IFRS Vs US GAAP

IFRS vs US GAAP a concept that compares two major accounting frameworks used worldwide. While IFRS is adopted in many jurisdictions, US GAAP governs financial reporting for applicable US entities. Both IFRS and US GAAP aim to ensure reliable financial reporting but differ in areas such as revenue recognition, inventory, … Read More

IFRS 6 – Exploration for and Evaluation of Mineral Resources

IFRS 6

The objective of IFRS 6 – Exploration for and Evaluation of Mineral Resources is to specify the financial reporting of the exploration for and evaluation of mineral resources. Last Updated – October, 2026 International Financial Reporting Standard IFRS 6 Exploration for and Evaluation of Mineral Resources A definitive reference for … Read More