The objective of IFRS 1 – First-time Adoption of International Financial Reporting Standards is to ensure that an entity’s first IFRS financial statements, and its interim financial reports for part of the period covered by those financial statements, contain high quality information.
Last Updated – October, 2026
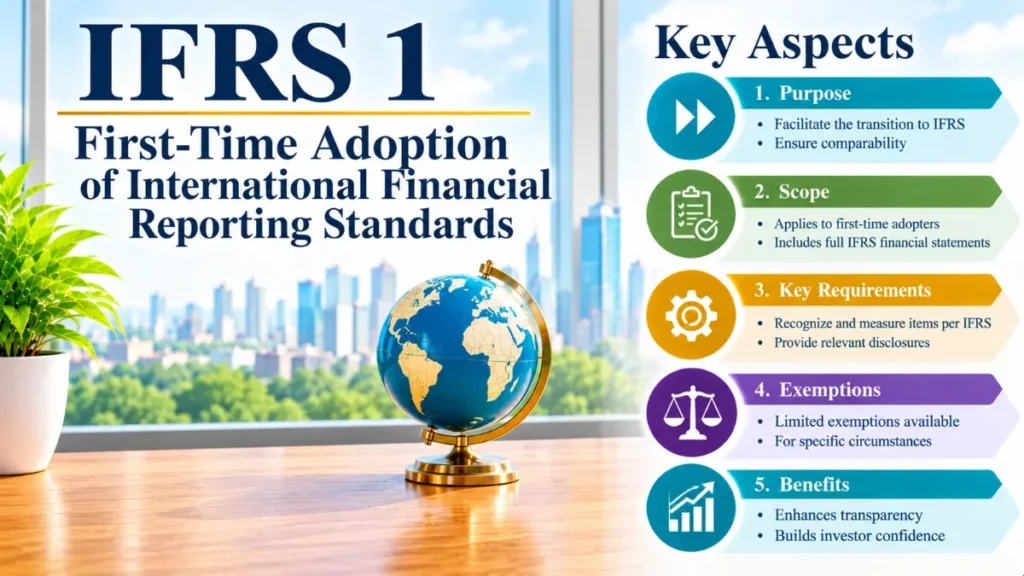
A clear, practical guide to IFRS 1; who it applies to, the transition steps, optional exemptions, mandatory exceptions, required disclosures and the questions practitioners ask most.
IFRS 1 sets out the procedures an entity must follow when it adopts International Financial Reporting Standards (IFRS) for the first time as the basis for its general-purpose financial statements.
The central requirement is straightforward; a first-time adopter must apply IFRS in full, retrospectively, as if it had always applied the standards, subject to specific, carefully bounded exemptions and exceptions that manage cost and practicability.
The result is financial statements that are transparent, comparable across entities and periods, and a faithful starting point for IFRS reporting going forward.
Scope of IFRS 1
IFRS 1 applies to an entity whose first IFRS financial statements are the first annual financial statements in which it makes an explicit and unreserved statement of compliance with IFRS. An entity is a first-time adopter if its most recent previous annual financial statements did not contain such a statement.
Typical scenarios that trigger IFRS 1 include:
Local GAAP to IFRS
An entity previously reporting under national standards (e.g., US GAAP, UK GAAP, Indian AS) that now adopts IFRS as its reporting framework.
Initial Public Offering
A company listing on a stock exchange that requires IFRS-compliant financial statements for the first time, having previously reported only for internal purposes.
Regulatory Mandate
A jurisdiction legislates the adoption of IFRS for public interest entities, requiring all qualifying companies to transition by a specified date.
Re-adoption of IFRS
An entity that previously used IFRS, then stopped, and now returns to IFRS may either apply IFRS 1 or apply IFRS retrospectively as if it had never stopped (IFRS 1.4A).
Key Definition – First IFRS Financial Statements
The entity’s first IFRS financial statements are the first annual financial statements in which the entity adopts IFRS by an explicit and unreserved statement of compliance with IFRS, in accordance with IAS 1 Presentation of Financial Statements.
How to Apply IFRS 1 (Steps for First-time Adoption)
IFRS 1 establishes a structured pathway so that the opening IFRS statement of financial position is a high-quality, reliable foundation. The key steps are:
Identify the Transition Date
The transition date is the beginning of the earliest period for which the entity presents full comparative IFRS information, generally the start of the prior year.
Prepare the Opening Statement of Financial Position
At the transition date, prepare a statement of financial position using accounting policies that comply with IFRS in force at the end of the first IFRS reporting period.
Recognise Required Assets & Liabilities
Recognise all assets and liabilities that IFRS requires, derecognise items IFRS does not permit, and reclassify items as IFRS requires.
Apply Measurement Requirements
Measure all recognised assets and liabilities by applying IFRS retrospectively, unless an optional exemption or mandatory exception applies.
Apply Exemptions & Exceptions
Elect any optional exemptions to reduce the cost of transition, and comply with all mandatory exceptions.
Disclose & Reconcile
Provide comparative information and detailed reconciliations explaining the effect of the transition from previous GAAP to IFRS.
The objective of IFRS 1 is to ensure that an entity’s first IFRS financial statements, and its interim financial reports for part of the period covered by those statements, contain high-quality information that is transparent for users.
Key Dates in the IFRS 1 Timeline
The example below assumes a 31 December reporting date and the minimum one year of comparative information.
Start of the Earliest Comparative Period
The date of the opening IFRS statement of financial position. IFRS is applied from this date, using the policies that will apply at the reporting date.
End of the Comparative Period
The comparative year is presented under IFRS, with reconciliations of equity and total comprehensive income from previous GAAP.
End of the First IFRS Reporting Period
The date of the first complete set of IFRS financial statements, including the primary statements, notes and the IFRS 1 disclosures.
Optional Exemptions Available Under IFRS 1
IFRS 1 provides a range of optional exemptions from full retrospective application. They are voluntary: an entity chooses whether to apply each one based on its circumstances. They exist because full retrospective application can be impractical or cost-prohibitive in certain areas.
Business Combinations
An entity need not restate business combinations that occurred before the transition date under IFRS 3. A prospective approach is permitted.
Property, Plant & Equipment
Fair value, or a previous GAAP revaluation, may be used as deemed cost for PP&E at the transition date, avoiding costly retrospective depreciation calculations.
Employee Benefits
Cumulative actuarial gains and losses may be recognised in full at the transition date, without restating the corridor method retrospectively.
Cumulative Translation Differences
Cumulative translation differences for all foreign operations may be deemed zero at the transition date, simplifying currency translation history.
Compound Financial Instruments
If the liability component of a compound instrument is no longer outstanding at the transition date, there is no need to split equity and liability components retrospectively.
Share-Based Payments
An entity is not required to apply IFRS 2 to equity instruments granted on or before specified dates, or to liabilities settled before the transition date.
Leases
Entities may assess whether an arrangement contains a lease at the transition date, and lessees may measure lease liabilities using the incremental borrowing rate at that date (IFRS 16 transition relief).
Insurance Contracts
First-time adopters may apply the transitional provisions of IFRS 17 rather than full retrospective application, easing the complexity of restating long-tail contracts.
Mandatory Exceptions to Retrospective Application
Unlike optional exemptions, mandatory exceptions prohibit retrospective application. The IASB concluded that, in these areas, the cost and the subjectivity or hindsight risk of retrospective application would undermine the reliability of financial information.
Estimates
Estimates at the transition date must be consistent with estimates made for the same date under previous GAAP (after adjusting for accounting policy differences), unless there is objective evidence of error. Hindsight is not permitted.
Derecognition of Financial Instruments
Financial assets and liabilities derecognised before the transition date under previous GAAP are not reinstated. The derecognition requirements apply prospectively.
Hedge Accounting
Hedge accounting is reflected only for relationships that meet the qualifying criteria of IFRS 9 at the transition date. Relationships that do not qualify cannot be designated retrospectively.
Non-Controlling Interests
Certain IFRS 10 requirements regarding non-controlling interests are applied prospectively from the transition date only, not retrospectively.
Classification & Measurement of Financial Assets
The classification of financial assets is based on the facts and circumstances existing at the transition date rather than at original recognition.
Impairment, Embedded Derivatives & Government Loans
IFRS 1 also restricts retrospective application for the impairment of financial assets, embedded derivatives and loans received from governments at a below-market rate of interest.
IFRS 1 Disclosure Requirements
The disclosure requirements under IFRS 1 are extensive. Their purpose is to help users understand the financial effect of the transition and how the opening IFRS figures differ from those reported under previous GAAP. Key disclosures include:
- Equity reconciliation: a reconciliation of equity under previous GAAP to equity under IFRS, at the transition date and at the end of the latest period presented in the most recent previous GAAP financial statements.
- Total comprehensive income reconciliation: a reconciliation of total comprehensive income reported under previous GAAP to IFRS for the comparative period.
- Explanatory notes: sufficient explanation of material adjustments to the statement of financial position, statement of comprehensive income and cash flows to enable users to understand the transition effects.
- Errors corrected: disclosure of any errors in previous GAAP financial statements that are corrected as part of the IFRS transition.
- Fair value as deemed cost: where fair value is used as deemed cost for an asset, disclosure of the aggregate of those fair values and the aggregate adjustment to previous GAAP carrying amounts.
- Optional exemptions elected: disclosure of which optional exemptions the entity has applied, enabling users to compare across first-time adopters.
- Interim reports: if the entity presents IFRS interim reports in the year of transition, additional reconciliation disclosures are required under IFRS 1.32–33.
The reconciliations required by IFRS 1 are among the most insightful disclosures in any financial report: they show the full effect of accounting policy differences on reported financial position and performance.
IFRS 1 Vs US GAAP – Key Differences in First-time Adoption
Although IFRS and US GAAP have converged on many issues, significant differences remain. Entities moving from US GAAP to IFRS commonly encounter adjustments in the following areas:
| Topic | US GAAP Treatment | IFRS Treatment | IFRS 1 Relief? |
|---|---|---|---|
| Inventory | LIFO permitted | LIFO prohibited; FIFO or weighted average | No |
| Development Costs | Generally expensed | Capitalised when criteria are met (IAS 38) | No specific exemption; IAS 38 criteria must have been met |
| PP&E Revaluation | Not permitted | Revaluation model allowed (IAS 16) | Yes, fair value as deemed cost |
| Business Combinations | ASC 805 | IFRS 3 (similar, but differences exist) | Yes, no restatement required |
| Leases | ASC 842 | IFRS 16 (single lessee model) | Yes, transition relief available |
| Financial Instruments | ASC 825 / ASC 326 | IFRS 9 (expected credit loss model) | Mandatory exceptions (e.g., derecognition) |
| Impairment Testing | Recoverability test for long-lived assets; no reversal | Recoverable amount (IAS 36); reversals permitted except goodwill | No |
| Provisions | Probable and reasonably estimable | More likely than not; discounted where material (IAS 37) | No |
Frequently Asked Questions
What is IFRS 1 and why does it exist?
IFRS 1 exists because moving to a new set of accounting standards is complex and potentially costly. Without a dedicated standard, entities would take inconsistent approaches to the transition, undermining comparability. IFRS 1 provides a structured pathway that ensures the opening IFRS statement of financial position is transparent and reliable, while allowing practical exemptions where full retrospective application would be unduly burdensome.
What is the “deemed cost” concept in IFRS 1?
Deemed cost is an amount used as a surrogate for cost or depreciated cost that would otherwise be determined under IFRS. IFRS 1 allows an entity to use fair value at the transition date as the deemed cost of items such as property, plant and equipment, investment property and certain intangible assets. This avoids reconstructing historical cost and depreciation records that may be impractical or unavailable.
Does IFRS 1 apply to interim financial reports?
Yes. If an entity presents an interim financial report under IAS 34 for part of the period covered by its first IFRS financial statements, IFRS 1 requirements apply. The interim report must include reconciliations showing the effect of the transition on equity and on profit or loss for the comparable interim period.
Can an entity choose not to restate comparative periods?
No. IFRS 1 requires at least one year of comparative information prepared under IFRS. The general rule is retrospective application from the transition date. The optional exemptions reduce the scope of restatement in specific areas, but they do not allow an entity to avoid presenting IFRS comparative information together with the required reconciliations.
How does IFRS 1 affect goodwill from past acquisitions?
Under the business combinations exemption, goodwill from pre-transition acquisitions is generally carried at its previous GAAP amount at the transition date, after an impairment test and any required adjustments. Goodwill is not amortised under IFRS, it is tested for impairment under IAS 36. Amortisation charged under previous GAAP is not reversed, but amortisation ceases going forward.
What happens to deferred taxes at transition?
Deferred taxes under IAS 12 must be recognised on temporary differences arising from the transition adjustments. IFRS 1 does not provide a dedicated exemption in this area, so entities recognise the deferred tax assets and liabilities that IFRS requires, including those arising from fair value adjustments and lease capitalisation. The effect is taken through retained earnings in the opening IFRS statement of financial position.
Primary source: IFRS Foundation. Always refer to the current authoritative text of the standard.
This article is for general educational and informational purposes only and does not constitute accounting, audit, tax or legal advice. Application of IFRS 1 depends on an entity’s specific facts and circumstances, consult a qualified professional before making reporting decisions.
(Qualified) Chartered Accountant – ICAP
Master of Commerce – HEC, Pakistan
Bachelor of Accounting (Honours) – AeU, Malaysia