The ‘core principle’ of IFRS 8 – Operating Segments is that an entity shall disclose information to enable users of its financial statements to evaluate the nature and financial effects of the business activities in which it engages and the economic environment(s) in which it operates.
Last Updated – October, 2026
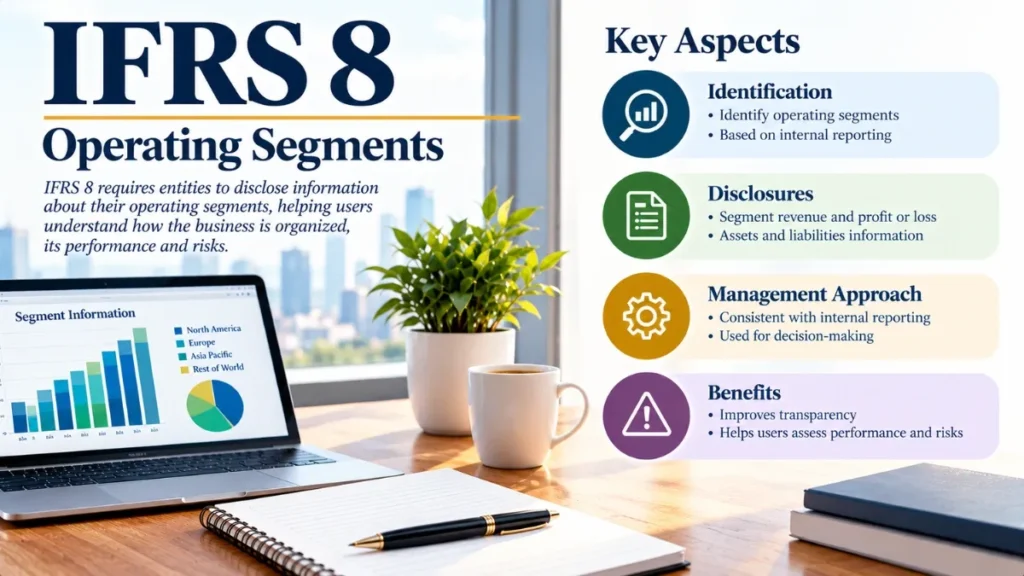
IFRS 8 – Operating Segments
A definitive guide to segment reporting; scope, criteria, thresholds, disclosures, and practical application for financial professionals.
IFRS 8 Overview and Objective
IFRS 8 Operating Segments is an International Financial Reporting Standard issued by the International Accounting Standards Board (IASB) in November 2006, effective for annual periods beginning on or after 1 January 2009. It replaced IAS 14 Segment Reporting and aligns closely with the US standard SFAS 131 (now ASC 280).
The standard establishes principles for an entity to disclose information about its operating segments, products and services, geographical areas, and major customers. Its goal is to help investors and other users of financial statements evaluate the nature and financial effects of the business activities in which an entity engages and the economic environments in which it operates.
“IFRS 8 requires entities to adopt the management approach to segment reporting, disclosing information that management uses internally to evaluate performance and allocate resources.”
Scope & Applicability of IFRS 8
IFRS 8 applies to the separate or individual financial statements of an entity, and to the consolidated financial statements of a group, whose debt or equity instruments are traded in a public market (including a domestic or foreign stock exchange or an over-the-counter market) or that files, or is in the process of filing, its financial statements with a securities commission or other regulatory organisation for the purpose of issuing any class of instruments in a public market.
Who Must Apply IFRS 8?
- ✓Entities with equity or debt securities listed on a public market
- ✓Entities in the process of listing (filing with a securities regulator)
Entities not meeting the above criteria such as private companies are not required to apply IFRS 8. However, if such an entity voluntarily elects to describe its financial information as segment information, it must comply with all requirements of the standard (IFRS 8, para. 2). This is a narrower obligation than mandatory applicability, it means a private entity is free not to report segments at all, but it cannot select IFRS 8’s requirements if it chooses to use the label.
Core Principle of Operating Segment Reporting
The core principle of IFRS 8 is that an entity shall disclose information to enable users of its financial statements to evaluate the nature and financial effects of the business activities it undertakes and the economic environments in which it operates.
This is achieved through the management approach, segments are identified on the basis of internal reports that are regularly reviewed by the entity’s Chief Operating Decision Maker (CODM), the function responsible for allocating resources to and assessing the performance of the entity’s operating segments.
The CODM is a function, not necessarily a single individual. It may be a chief executive officer, a board of directors, or an operating committee. The key test is who makes decisions about resource allocation and performance assessment.
How to Identify an Operating Segment
An operating segment is a component of an entity that meets all three of the following criteria:
- 1Engages in business activities from which it may earn revenues and incur expenses (including revenues and expenses relating to transactions with other components of the same entity).
- 2Whose operating results are regularly reviewed by the CODM to make decisions about resources to be allocated to the segment and to assess its performance.
- 3For which discrete financial information is available.
A component that sells primarily or exclusively to other operating segments but whose segment performance is reviewed separately may still qualify as an operating segment.
Certain corporate headquarters or functional departments that do not earn revenues (or earn only incidental revenues) are not operating segments, but they represent unallocated reconciling items.
Reportable Operating Segments Under IFRS 8
Not every operating segment needs to be separately reported. An entity must separately disclose information about an operating segment if it meets any one of the quantitative thresholds described below. Additionally, aggregation is permitted under certain conditions.
Aggregation Criteria
Two or more operating segments may be aggregated into a single reportable segment if aggregation is consistent with the core principle of IFRS 8, the segments have similar economic characteristics, and the segments are similar in each of the following respects:
- aThe nature of the products and services
- bThe nature of the production processes
- cThe type or class of customer for their products and services
- dThe methods used to distribute their products or provide their services
- eIf applicable, the nature of the regulatory environment
Quantitative Thresholds – The 10% Tests
An operating segment is a reportable segment if it meets any one of the following quantitative thresholds:
| Threshold | Criteria | Basis |
|---|---|---|
| Revenue ≥ 10% | Reported revenue (internal & external) is 10% or more of combined revenue of all operating segments | Combined internal + external revenue |
| Profit/Loss ≥ 10% | Absolute profit or loss is 10% or more of the greater of: (i) combined profit of all profitable segments, or (ii) combined loss of all loss-making segments | Greater absolute amount |
| Assets ≥ 10% | Assets are 10% or more of combined assets of all operating segments | Segment assets as reviewed by CODM |
Reportable segments must collectively account for at least 75% of total external revenue. If they do not, additional segments must be identified as reportable (even if they do not meet the thresholds) until the 75% level is reached.
There is also a practical ceiling, if the number of reportable segments identified exceeds ten, the entity should consider whether a practical limit has been reached and aggregation is appropriate.
IFRS 8 Disclosure Requirements
IFRS 8 requires extensive qualitative and quantitative disclosures about each reportable segment. These are organised into general information, segment profit/loss and assets/liabilities, and reconciliations.
General Information
Entities must disclose the factors used to identify their reportable segments, including the basis of organisation (e.g., differences in products and services, geographical areas, regulatory environments, or a combination). They must also describe the types of products and services from which each reportable segment derives its revenues.
Segment Profit or Loss
For each reportable segment, the following must be disclosed if included in the measure of segment profit or loss reviewed by the CODM, or otherwise regularly provided to the CODM:
- →Revenues from external customers
- →Revenues from transactions with other operating segments
- →Interest revenue and interest expense
- →Depreciation and amortisation
- →Material items of income and expense (per IAS 1)
- →The entity’s interest in the profit/loss of associates and joint ventures accounted for by the equity method
- →Income tax expense or income
- →Material non-cash items other than depreciation and amortisation
Segment Assets and Liabilities
Total assets and total liabilities for each reportable segment must be disclosed if those amounts are regularly provided to the CODM. If only assets are provided to the CODM, only assets need be reported. Capital expenditure (additions to non-current assets) must also be disclosed if included in the CODM’s information.
Segment Measurement and Reconciliation
A key feature of IFRS 8 is that the measurement basis is whatever the CODM uses internally, it does not need to comply with the accounting policies applied in the consolidated financial statements. For example, a segment may be measured using a non-GAAP performance metric such as EBITDA or adjusted operating profit.
Because of this flexibility, IFRS 8 requires reconciliations of the reported segment totals to the corresponding amounts in the entity’s financial statements. Specifically, para. 28 requires reconciliations for: total segment revenues, total segment profit or loss, total segment assets, total segment liabilities (if disclosed), and the total of every other material segment item disclosed. The reconciliation covers only the items actually reported or disclosed, it does not extend to every conceivable financial metric. All material reconciling items must be separately identified and described.
Reconciliation – Key Principle
Any difference between the measure of segment performance used by management and the amounts recognised in the primary financial statements must be explained. Common reconciling items include: unallocated corporate costs, inter-segment eliminations, different depreciation policies, and deferred tax adjustments.
Entity-Wide Disclosures Under IFRS 8
In addition to segment-level disclosures, IFRS 8 requires certain entity-wide disclosures even if the entity has only one reportable segment. These disclosures provide investors with a geographic and customer-concentration view of the business.
| Disclosure Category | Required Information |
|---|---|
| Products & Services | Revenues from external customers for each product or service (or each group of similar products/services), unless the necessary information is not available and the cost to develop it would be excessive. |
| Geographical Areas | Revenues from external customers attributed to the entity’s country of domicile and all foreign countries in total; non-current assets located in the country of domicile and in all foreign countries in total. Material countries must be disclosed separately. |
| Major Customers | If revenues from transactions with a single external customer amount to 10% or more of total revenues, the entity must disclose that fact, the total amount of revenues from each such customer, and the identity of the segment(s) reporting those revenues. |
IFRS 8 Practical Examples
Example 1 – Identifying the CODM
A multinational consumer goods company has a Group CEO who is supported by a divisional performance committee that meets monthly to review segment results and approve capital budgets. The committee, not the CEO alone is the CODM because it is the collective body that makes resource allocation decisions. Each division (Food & Beverages, Personal Care, Home Products) reviewed by this committee is an operating segment.
Example 2 – Applying the 10% Revenue Threshold
Note: This is a simplified illustration assuming no inter-segment (internal) revenue. In practice, the IFRS 8 revenue threshold is tested against each segment’s total reported revenue both external and internal compared to the combined revenue of all operating segments (para. 13(a)).
A technology group has five operating segments. For simplicity, assume no inter-segment revenue, so reported revenue equals external revenue: $400M, $150M, $90M, $80M, and $30M, totalling $750M. Testing each segment against 10% of $750M ($75M): Segment A ($400M – 53%), Segment B ($150M – 20%), Segment C ($90M – 12%), and Segment D ($80M – 11%) each exceed the threshold and are individually reportable. Segment E ($30M – 4%) falls below all three quantitative thresholds.
The 75% external revenue coverage test – Segments A-D together contribute $720M out of $750M total external revenue (96%), which comfortably exceeds the 75% floor. The 75% threshold is therefore already satisfied. Segment E does not need to be separately reported to meet the coverage rule. It would instead be disclosed in aggregate under an “all other segments” category alongside any other non-reportable segments (IFRS 8, para. 16), with a reconciliation to total entity revenue.
Example 3 – Non-GAAP Segment Measure
A retail chain’s CODM reviews segment performance using “Contribution Margin” (revenues less cost of goods sold and directly attributable store costs), which excludes depreciation, head-office overheads, and finance costs. IFRS 8 permits this measure to be used for disclosure. However, the entity must reconcile the total Contribution Margin of all segments back to profit before tax in the consolidated statement of profit or loss, clearly explaining unallocated depreciation ($42M), corporate costs ($18M), and finance costs ($11M).
IFRS 8 vs IAS 14 – Key Differences
IFRS 8 represented a significant shift from its predecessor, IAS 14 Segment Reporting, in both philosophy and requirements.
| Aspect | IAS 14 | IFRS 8 |
|---|---|---|
| Approach | Risks & rewards approach – segments defined by external reporting logic | Management approach – segments defined by internal reporting |
| Measurement | Required compliance with IFRS accounting policies | Uses management’s internal measures (non-GAAP permitted) |
| Primary vs Secondary | Required primary and secondary segments (business and geographic) | Single tier of reportable segments; geographic info via entity-wide disclosures |
| Liabilities | Segment liabilities required for primary segments | Only if regularly provided to CODM |
Frequently Asked Questions
Does IFRS 8 apply to private companies?
Can a company have only one reportable segment?
What is the difference between an operating segment and a reportable segment?
How should inter-segment revenues be treated?
Does IFRS 8 require disclosure of segment liabilities?
What disclosures are required about major customers?
When did IFRS 8 become effective?
(Qualified) Chartered Accountant – ICAP
Master of Commerce – HEC, Pakistan
Bachelor of Accounting (Honours) – AeU, Malaysia