IFRS 9 Vs IAS 39 (Financial Instruments) – Key Differences
IFRS 9 Vs IAS 39

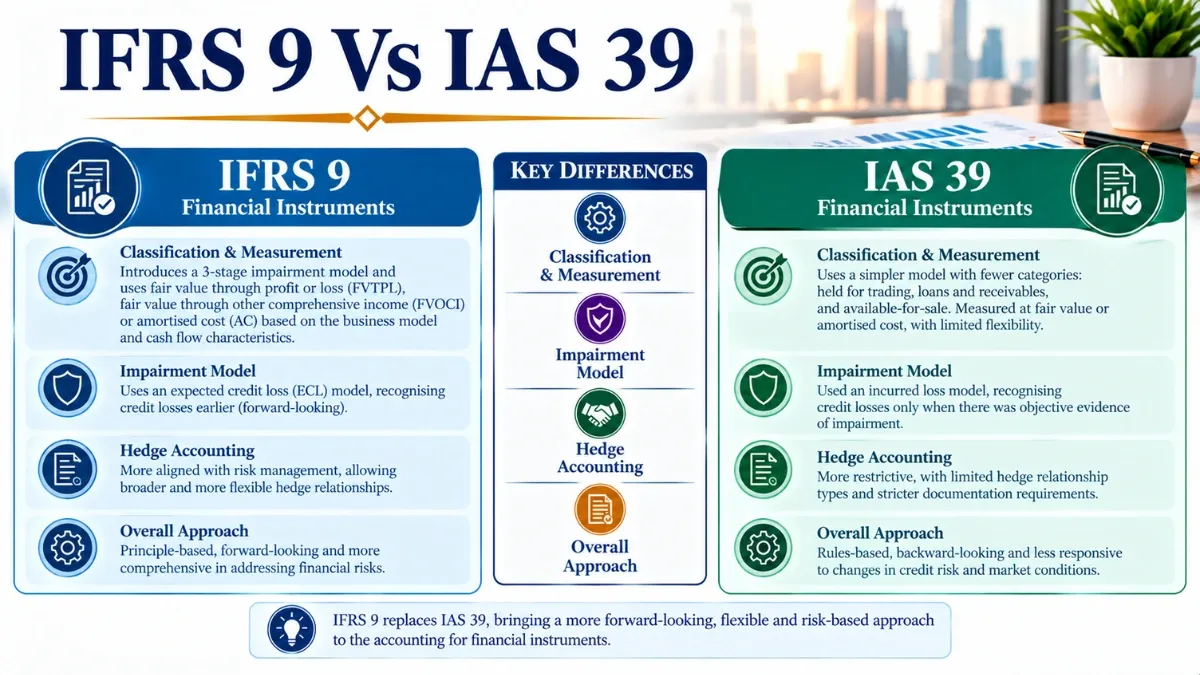
The one difference amongst many of IFRS 9 vs IAS 39 concept is the key difference in relation to the approach of impairment. IFRS 9 uses ‘Expected Credit Losses‘ (ECLs) to recognize impairment losses on financial assets, as compared to IAS 39 ‘Incurred Losses’. Last Updated – March, 2026 Financial … Read More
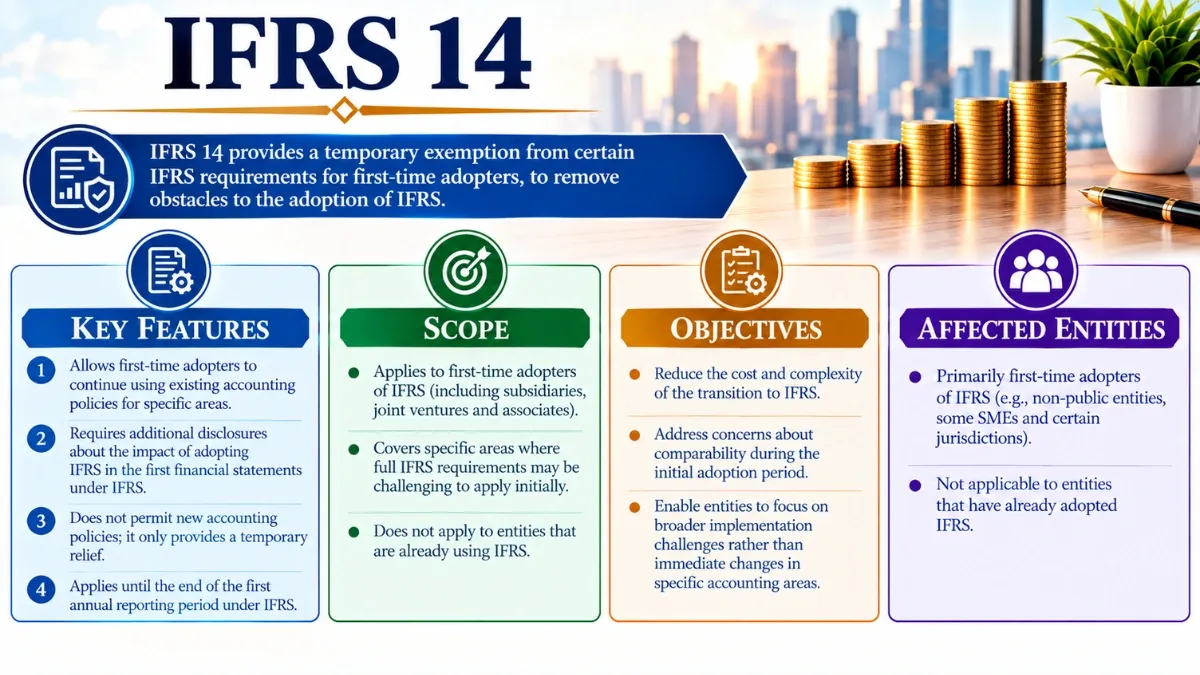
IFRS 14 – Regulatory Deferral Accounts

IFRS 14

The objective of IFRS 14 – Regulatory Deferral Accounts is to specify the financial reporting requirements for ‘regulatory deferral account balances’ that arise when an entity provides goods or services to customers at a price or rate that is subject to rate regulation. Last Updated – March, 2026 IASB International … Read More

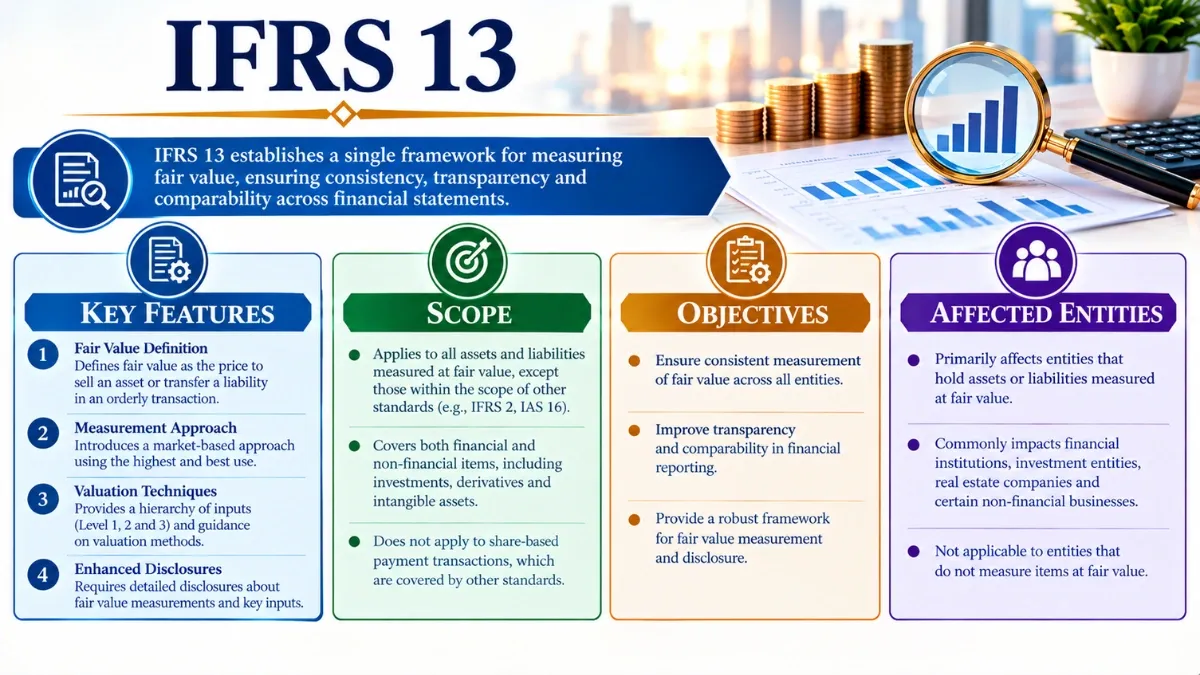
IFRS 13 – Fair Value Measurement

IFRS 13

IFRS 13 – Fair Value Measurement: Last Updated – March, 2026 IFRS Standard · IASB IFRS 13 – Fair Value Measurement The definitive guide to understanding fair value measurement under International Financial Reporting Standards, from the three-level hierarchy to disclosure obligations. Effective Since 1 Jan 2013 Issued By IASB Reading … Read More

IFRS 12 – Disclosure of Interests in Other Entities

IFRS 12

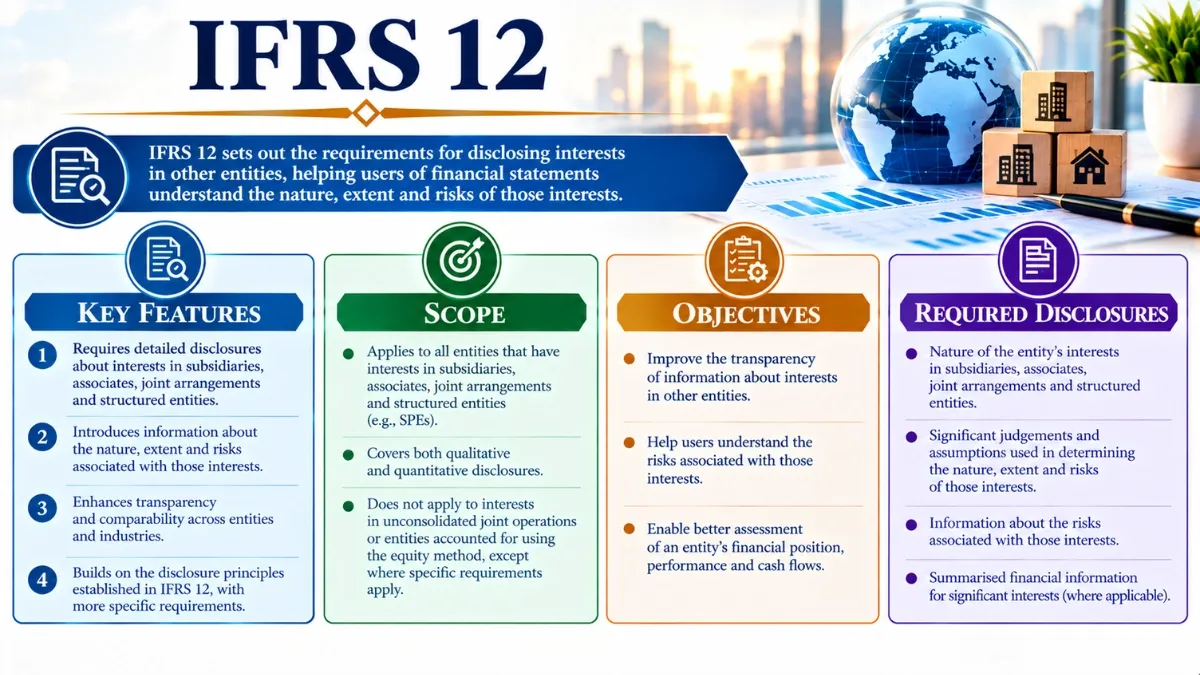
The objective of IFRS 12 – Disclosure of Interests in Other Entities is to require an entity to ‘disclose‘ information that enables users of its financial statements to evaluate: Last Updated – March, 2026 IASB International Financial Reporting Standard IFRS 12 – Disclosure of Interestsin Other Entities A comprehensive reference … Read More

IFRS 11 – Joint Arrangements

IFRS 11

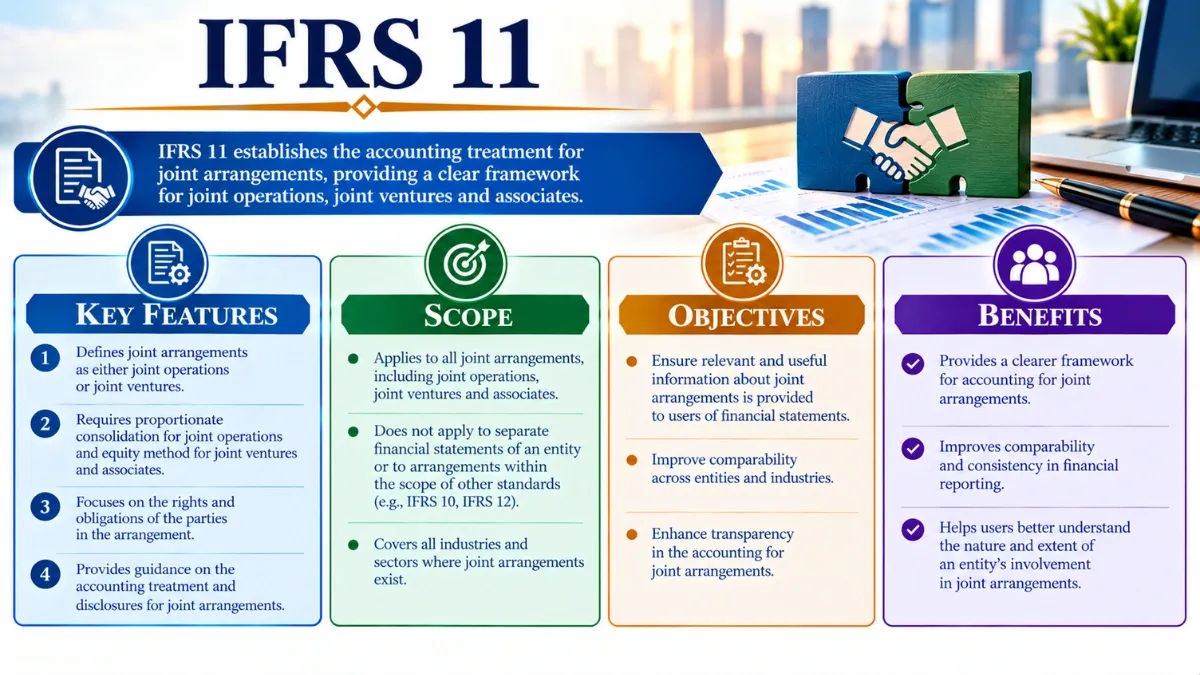
The objective of IFRS 11 – Joint Arrangements is to establish principles for ‘financial reporting’ by entities that have an interest in arrangements that are controlled jointly (i.e. joint arrangements). Last Updated – March, 2026 International Financial Reporting Standards IFRS 11 – Joint Arrangements CA Written by Jhanzayb ACA Qualified … Read More

IFRS 3 – Business Combinations

IFRS 3

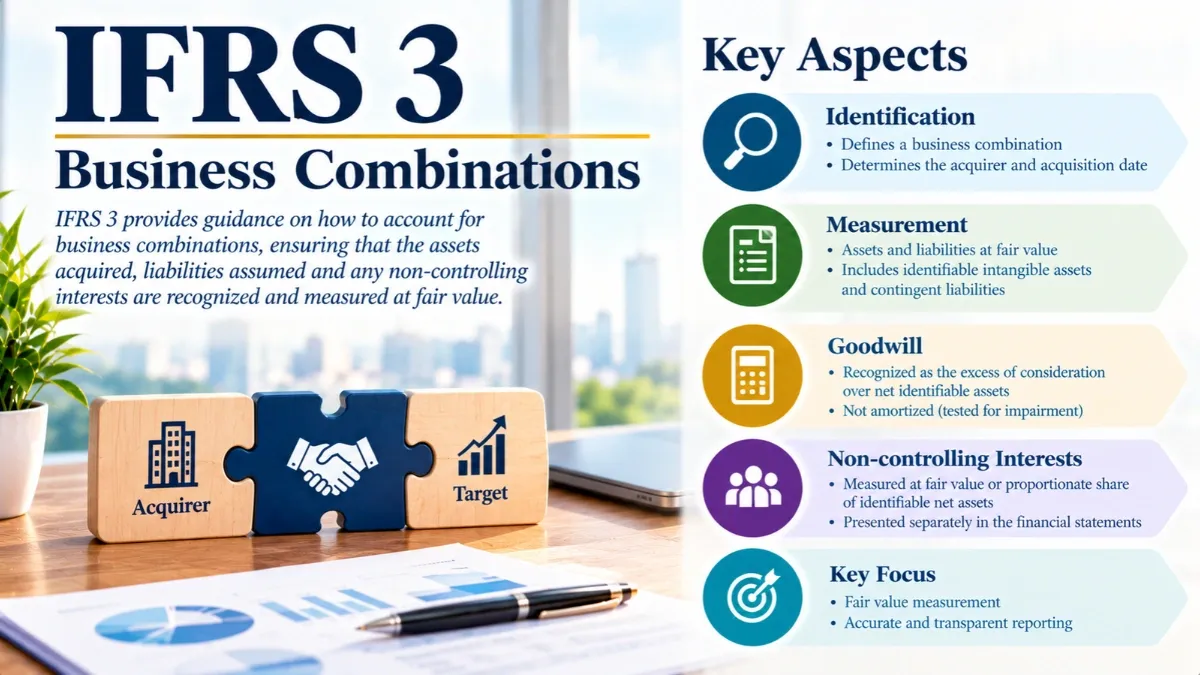
The objective of IFRS 3 – Business Combinations is to improve the relevance, reliability and comparability of the information that a reporting entity provides in its financial statements about a business combination and its effects. Last Updated – March, 2026 Home › Accounting › IFRS 3 International Financial Reporting Standard … Read More

IAS 37—Provisions, Contingent Liabilities and Contingent Assets

ias 37

IAS 37 OUTLINES the accounting for provisions (liabilities of uncertain timing or amount), together with contingent assets (possible assets) and contingent liabilities (possible obligations and present obligations that are not probable or not reliably measurable). IAS 37 – Provisions A liability of UNCERTAIN timing or amount. Provisions are RECOGNIZED when all … Read More