The objective of IFRS 6 – Exploration for and Evaluation of Mineral Resources is to specify the financial reporting of the exploration for and evaluation of mineral resources.
Last Updated – October, 2026
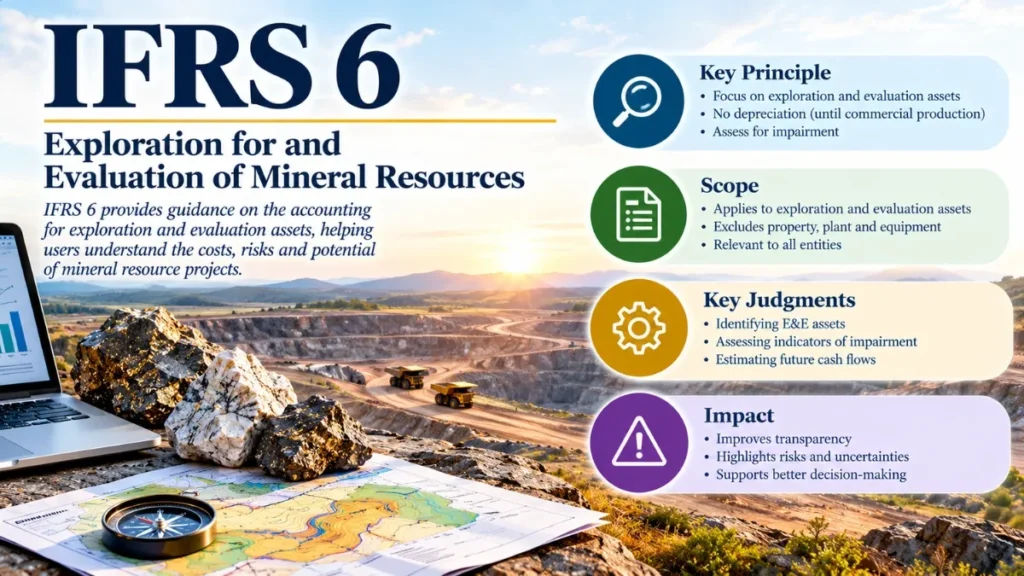
IFRS 6
Exploration for and Evaluation of Mineral Resources
A definitive reference for finance professionals, auditors, and investors navigating the unique accounting landscape of the extractive industries.
§ 01 — Introduction
What Is IFRS 6?
IFRS 6, Exploration for and Evaluation of Mineral Resources, is the International Financial Reporting Standard that governs how entities account for costs incurred in the search for mineral resources including oil, gas, ores, and other minerals before the technical feasibility and commercial viability of extracting those resources has been established.
Issued by the International Accounting Standards Board (IASB) in December 2004 and effective for annual periods beginning on or after 1 January 2006, IFRS 6 represents a deliberate policy of limited standardisation. It was conceived as an interim measure to prevent entities from having to change their existing accounting policies while the IASB undertook a more comprehensive review of extractive industry accounting.
“The Standard permits an entity to develop an accounting policy for exploration and evaluation assets without specifically considering the requirements of IFRS Framework paragraphs 8–10.” — IASB, IFRS 6 Basis for Conclusions, BC7
The practical effect is that entities operating in mining, oil and gas, and related sectors retain considerable flexibility in how they capitalise or expense exploration costs, a feature that distinguishes IFRS 6 from most other IFRS standards that demand strict adherence to the Conceptual Framework.
§ 02 — Scope & Application
Scope of IFRS 6
The scope of IFRS 6 is deliberately narrow. Understanding precisely which activities fall within its boundaries is essential for correct financial reporting in the extractive sector.
Activities Within Scope
IFRS 6 applies to expenditures incurred by an entity in connection with the exploration for and evaluation of mineral resources. Broadly, this encompasses the phase between the acquisition of legal rights to explore and the point at which technical feasibility and commercial viability are demonstrable.
Searching for Minerals
Gathering topographical, geological, geochemical, and geophysical data to locate potential mineral deposits.
Exploratory Drilling
Sampling, test-well drilling, and trenching activities undertaken to assess the size, grade, and continuity of a deposit.
Rights Acquisition
Costs directly associated with acquiring the legal rights and licences to explore a specific area.
Feasibility Studies
Technical and commercial assessments up to but not including the point of proven feasibility.
Activities Outside Scope
IFRS 6 explicitly does not apply to expenditures incurred before the entity obtains the legal rights to explore in a specific area (pre-licence costs), nor to development expenditures after technical feasibility and commercial viability have been established. Those phases are governed by IAS 16, IAS 38, or IFRS 9 as appropriate.
| Phase | Applicable Standard | Typical Treatment |
|---|---|---|
| Pre-licence / prospecting Outside IFRS 6 scope | IFRS Conceptual Framework; IAS 38 where relevant | Typically expensed; treatment depends on the nature of the expenditure and applicable standard |
| Exploration & evaluation | IFRS 6 | Capitalise or expense per policy |
| Development | IAS 16 / IAS 38 | Capitalise as PP&E or intangible |
| Production | IAS 2 / IAS 16 | Depletion and amortisation |
| Decommissioning | IAS 37 / IFRIC 1 | Provision recognition |
§ 03 — Recognition
Recognition of Exploration and Evaluation Assets
One of the most significant features of IFRS 6 is the leverage it grants entities in developing their recognition policies. Rather than mandating a single approach, the standard permits entities to continue using accounting policies developed under previous national GAAPs, provided those policies result in information that is relevant and reliable.
The Area-of-Interest Method
The most widely adopted approach in practice is the area-of-interest method, under which all E&E expenditures relating to a defined geographical area are accumulated and capitalised as an asset, pending the outcome of exploration activities. If the area is abandoned, costs are written off; if it progresses to development, costs are reclassified to development assets.
The Full Cost Method
IFRS 6 does not prescribe a single recognition method; it permits entities to retain policies developed under previous GAAPs, provided those policies meet the relevance and reliability criteria of paragraph 6. One such legacy approach is the full cost method, under which E&E costs are pooled within a broad cost centre rather than tracked area by area. It is important to note that this approach originated in national GAAPs (notably US GAAP and pre-IFRS Canadian GAAP) and is not a method expressly defined by IFRS 6 itself. Entities that apply it under IFRS do so by virtue of the standard’s transitional flexibility, and its use requires careful justification and consistent application.
Key Recognition Principle
When an entity develops or changes its accounting policy for E&E assets, the policy must make the financial statements more relevant and no less reliable or equally reliable and more relevant than under the previous policy. This is a lower bar than the full Conceptual Framework criteria, but it is not unlimited discretion.
Entities must also disclose the policy adopted, ensuring users can understand and compare reported figures.
Elements That May Be Capitalised
- Acquisition of rights to explore; licence fees, option payments, and directly attributable legal costs.
- Topographical, geological, geochemical, and geophysical studies directly relating to the exploration area.
- Exploratory drilling, including sample collection, core analysis, and down-hole testing.
- Activities related to evaluating the technical feasibility and commercial viability of extracting a resource.
- Depreciation on plant and equipment used in the E&E phase, to the extent directly attributable.
§ 04 — Measurement & Classification
Measurement of Exploration and Evaluation Assets
Under IFRS 6 paragraph 8, exploration and evaluation assets must be measured at cost on initial recognition. After that initial recognition, paragraph 12 permits an entity to apply either the cost model or the revaluation model consistently across all E&E assets of the same type. The mechanics of each subsequent measurement model are governed by IAS 16 (for tangible assets) and IAS 38 (for intangible assets) respectively.
Classification: Tangible or Intangible?
Entities must classify E&E assets as either tangible or intangible depending on the nature of the expenditure. In practice, many entities adopt a mixed approach classifying drilling rigs, vehicles, and infrastructure as tangible, and rights, licences, and geological data as intangible.
Tangible E&E Assets
Physical plant and equipment used in exploration such as drilling rigs, vehicles, sample storage facilities. Governed by IAS 16 after recognition.
Intangible E&E Assets
Rights, licences, permits, data, and technical knowledge arising from exploration activities. Governed by IAS 38 after recognition.
Reclassification to Development Assets
Once an entity determines that a mineral deposit is technically feasible and commercially viable to extract, E&E assets relating to that area must be reclassified out of E&E assets into the appropriate development asset category. This reclassification triggers full IFRS impairment testing under IAS 36 at the point of transition.
Exploration Commences
Legal rights to explore are acquired. E&E expenditure begins to be capitalised (or expensed) per the entity’s accounting policy.
Ongoing E&E Phase
Costs accumulate. IFRS 6 impairment indicators are monitored at each reporting date. Amortisation is not typically applied during the E&E phase because the asset has not yet been brought into use for production, the entity has not yet established the recoverable quantities that would form the basis for a depletion charge.
Technical Feasibility Established
Proved/probable reserves are determined. E&E assets are tested for impairment under IFRS 6, then reclassified to development assets.
Development & Production
Assets are now governed by IAS 16/38. Depletion and amortisation commences on a units-of-production or straight-line basis.
§ 05 — Impairment
IFRS 6 Impairment Testing and Indicators of Impairment
IFRS 6 establishes a modified impairment testing framework that departs materially from the IAS 36 model. Rather than conducting detailed recoverable amount calculations at every reporting date, entities need only assess E&E assets for impairment when specific facts and circumstances indicate that the carrying amount may exceed the recoverable amount.
Impairment Indicators Under IFRS 6
IFRS 6 paragraph 20 lists non-exhaustive indicators that should prompt an impairment assessment:
- Licence expiry: The period for which the entity has the right to explore in a specific area has expired or will expire in the near future, and is not expected to be renewed.
- Absence of budget: Substantive expenditure on further exploration and evaluation in the specific area is neither budgeted nor planned.
- Insufficient discovery: Exploration and evaluation has not led to the discovery of commercially viable quantities of mineral resources, and the entity has decided to discontinue such activities.
- Data suggesting non-recovery: Sufficient data exists to indicate that, although a development in the specific area is likely to proceed, the carrying amount of the exploration and evaluation asset is unlikely to be recovered in full from successful development or by sale.
Cash-Generating Units for E&E Assets
IFRS 6 permits a unique aggregation approach for identifying whether impairment exists: E&E assets may be grouped into CGUs (or groups of CGUs) that are no larger than an operating segment as defined by IFRS 8. This is more permissive than the standard IAS 36 CGU definition and allows an entity to assess recoverability at a higher level of aggregation. It means a stronger area within the segment may support the carrying value of a weaker one at the identification stage but this does not override the IAS 36 measurement requirements that apply once impairment is confirmed.
“The level at which E&E assets are assessed for impairment shall be no larger than an operating segment determined in accordance with IFRS 8.” — IFRS 6, paragraph 21
Once an impairment loss is identified, however, the measurement of that loss must follow IAS 36, meaning it equals the excess of carrying amount over recoverable amount (higher of fair value less costs of disposal and value in use).
§ 06 — Disclosure
IFRS 6 Disclosure Requirements
Despite its permissive stance on recognition and measurement, IFRS 6 imposes meaningful disclosure requirements designed to enable users of financial statements to understand the amounts arising from E&E activities and the judgements made.
| Disclosure Category | Required Information |
|---|---|
| Accounting policies | The accounting policy adopted for E&E expenditure, including the criteria used to determine recognition as an asset. |
| Amounts in financial statements | Amounts of assets, liabilities, income, and expenses arising from E&E activities; the carrying amounts of E&E assets. |
| Cash flow information | Operating, investing, and financing cash flows arising from E&E activities. |
| Impairment | When an impairment loss is recognised or reversed, disclosures required by IAS 36 must be provided. |
| Changes in policy | If an entity changes its E&E accounting policy, disclosure of the reason, nature, and financial effect of the change per IAS 8. |
Entities in the extractive industries often supplement mandatory IFRS 6 disclosures with reserve quantities disclosures, production information, and lifting cost data particularly where they are cross-listed on exchanges such as the NYSE or LSE that have additional reserve reporting requirements.
§ 07 — FAQs
Frequently Asked Questions
(Qualified) Chartered Accountant – ICAP
Master of Commerce – HEC, Pakistan
Bachelor of Accounting (Honours) – AeU, Malaysia