ISA 450 – Evaluation of Misstatements Identified during the Audit

ISA 450

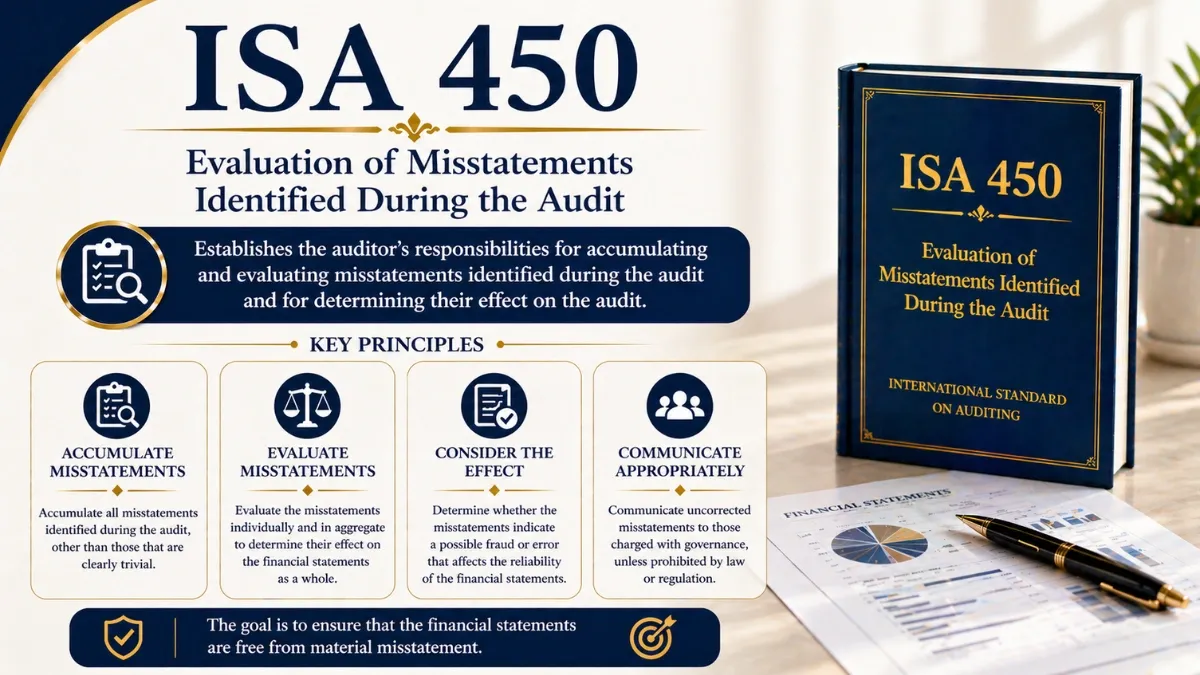
ISA 450 – Evaluation of Misstatements Identified during the Audit deals with the auditor’s responsibility to evaluate the effect of identified misstatements on the ‘audit’ and of uncorrected misstatements on the financial statements. Last Updated – April, 2026 Entrepreneurial Hub Home Audit ISA 450 International Standard on Auditing ISA 450 … Read More
IAS 23 – Borrowing Costs

IAS 23

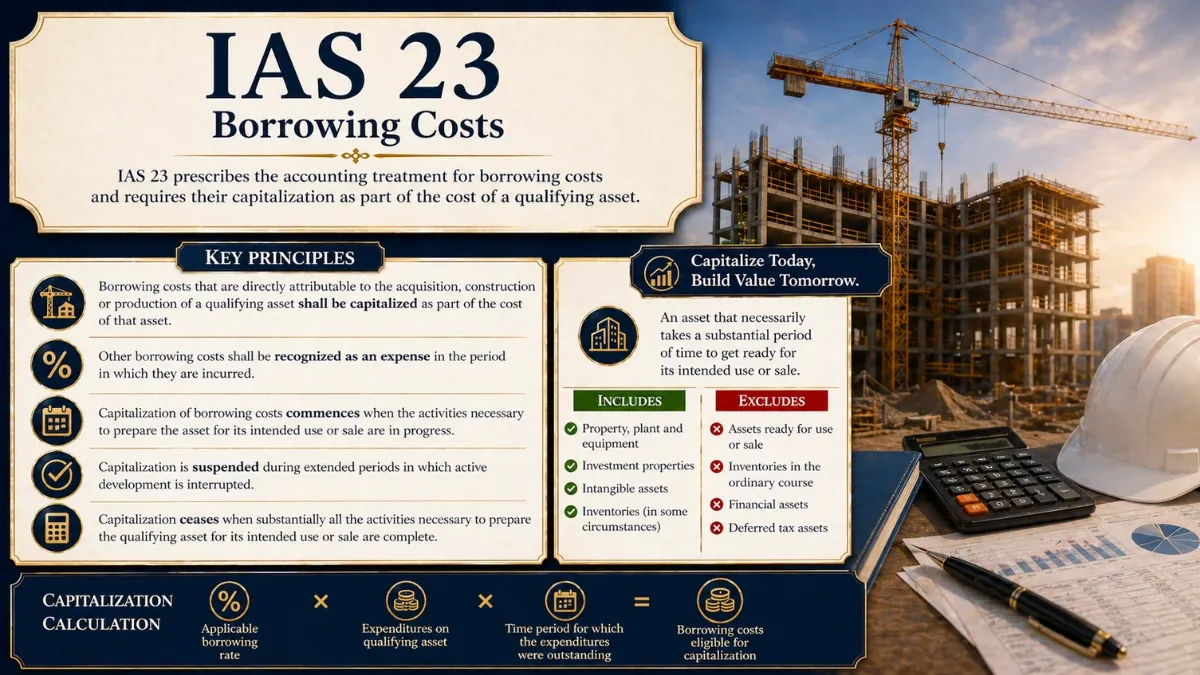
IAS 23 – Borrowing Costs requires that borrowing costs directly attributable to the acquisition, construction or production of a ‘qualifying asset’ (one that necessarily takes a substantial period of time to get ready for its intended use or sale) are included in the cost of the asset. Other borrowing costs … Read More

ISA 230 – Audit Documentation

ISA 230

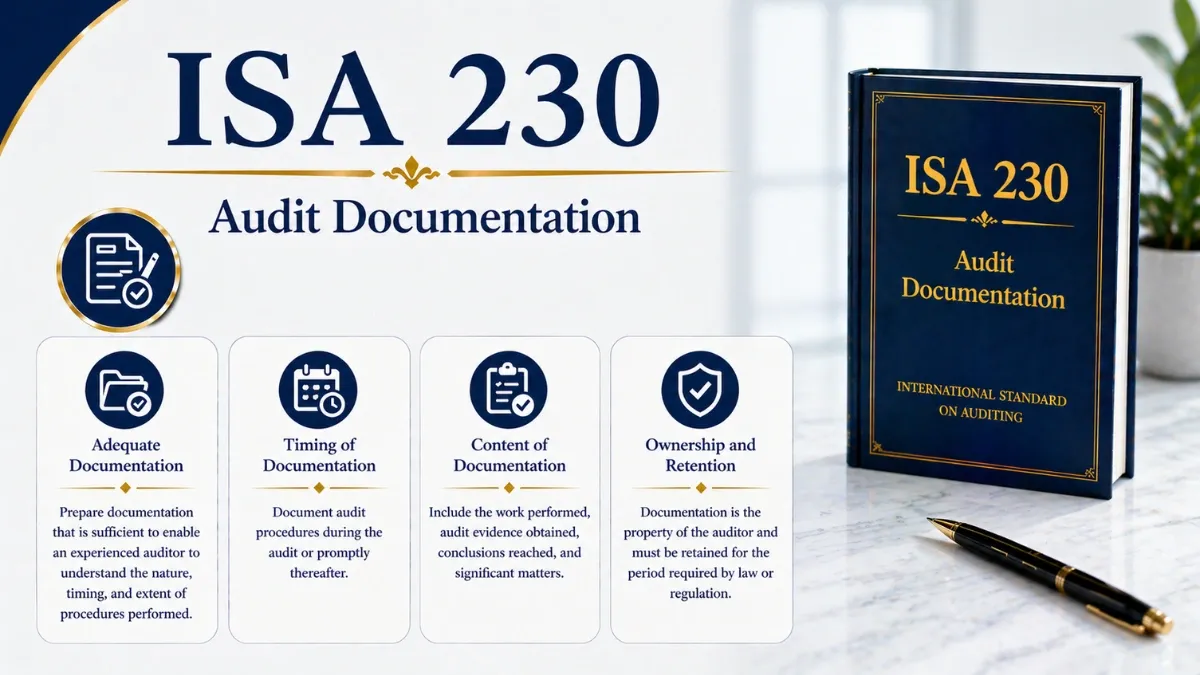
ISA 230 – Audit Documentation deals with the auditor’s responsibility to prepare audit documentation for an ‘audit‘ of financial statements. Last Updated – April, 2026 IAASB · International Standard on Auditing ISA 230 – Audit Documentation A complete reference guide to the auditor’s responsibilities for preparing, assembling, and retaining audit … Read More

ISA 505 – External Confirmations

ISA 505

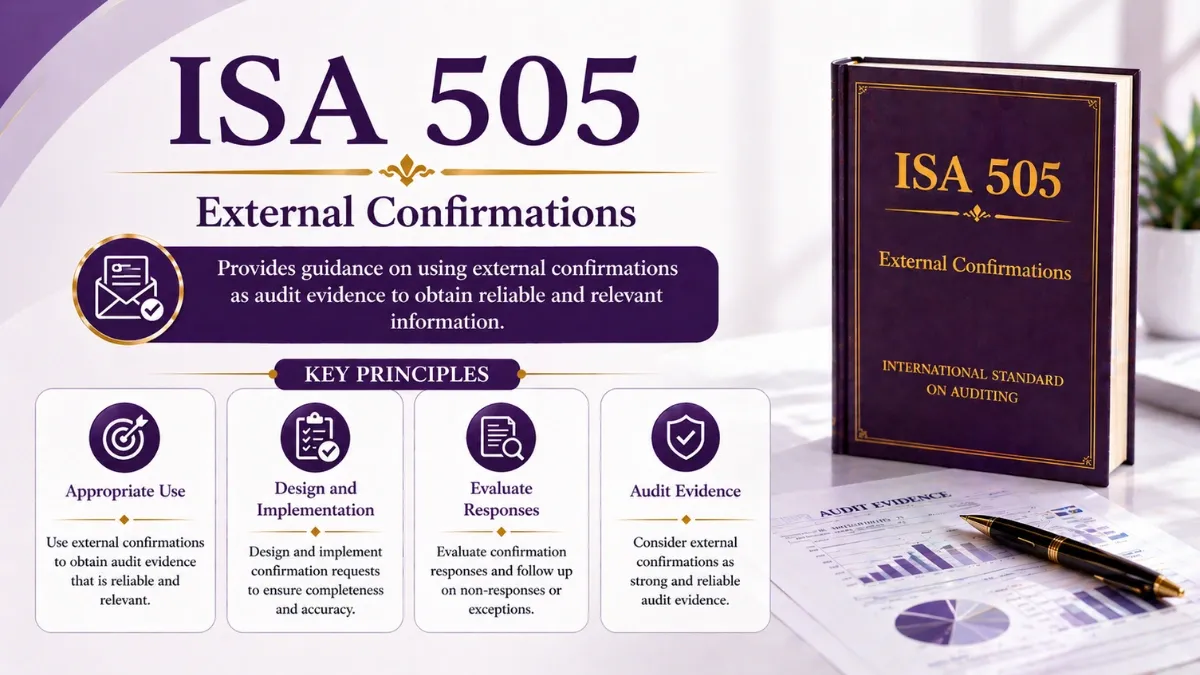
ISA 505 – External Confirmations deals with the auditor’s use of external confirmation procedures to obtain audit evidence in accordance with the requirements of ISA 330 (The Auditor’s Responses to Assessed Risks) and ISA 500 (Audit Evidence). Last Updated – April, 2026 Home Audit ISA 505 International Standard on Auditing … Read More

ISA 800 (Revised) – Special Considerations—Audits of Financial Statements Prepared in Accordance with Special Purpose Frameworks

ISA 800

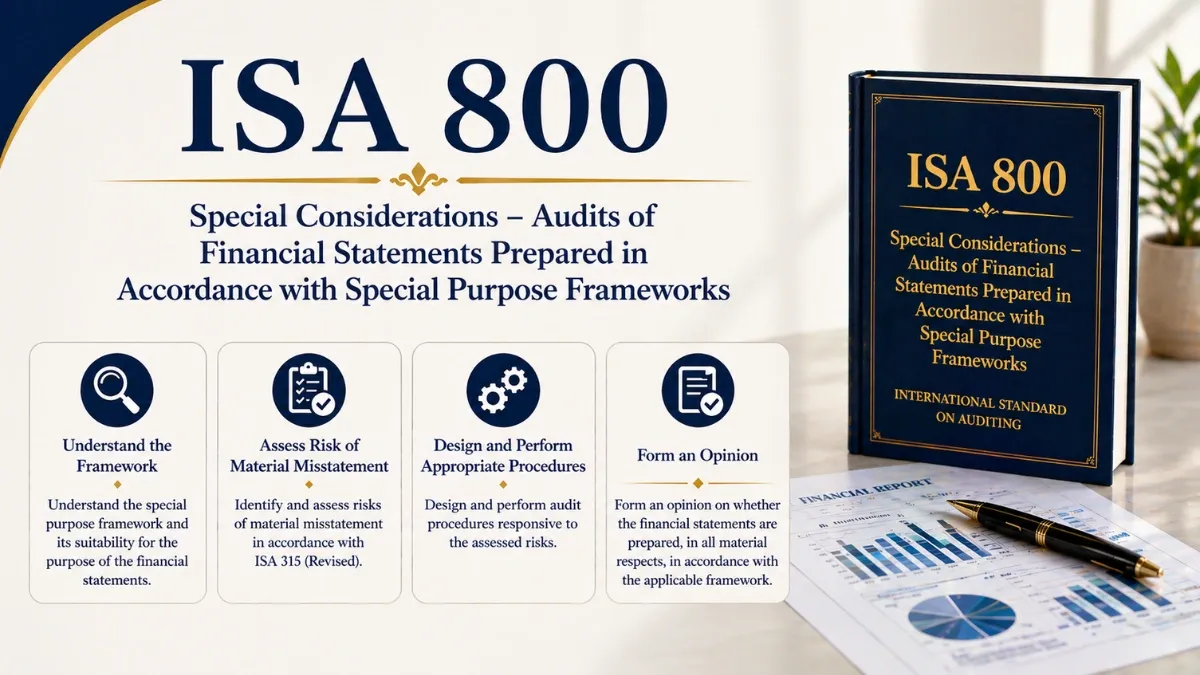
ISA 800 (Revised) – Special Considerations (Audits of Financial Statements Prepared in Accordance with Special Purpose Frameworks) deals with special considerations in the application of (ISAs 100-700) to an audit of financial statements prepared in accordance with a ‘special purpose framework’. Last Updated – April, 2026 ENTREPRENEURIAL HUB International Standard … Read More

ISA 570 (Revised 2024) – Going Concern

ISA 570

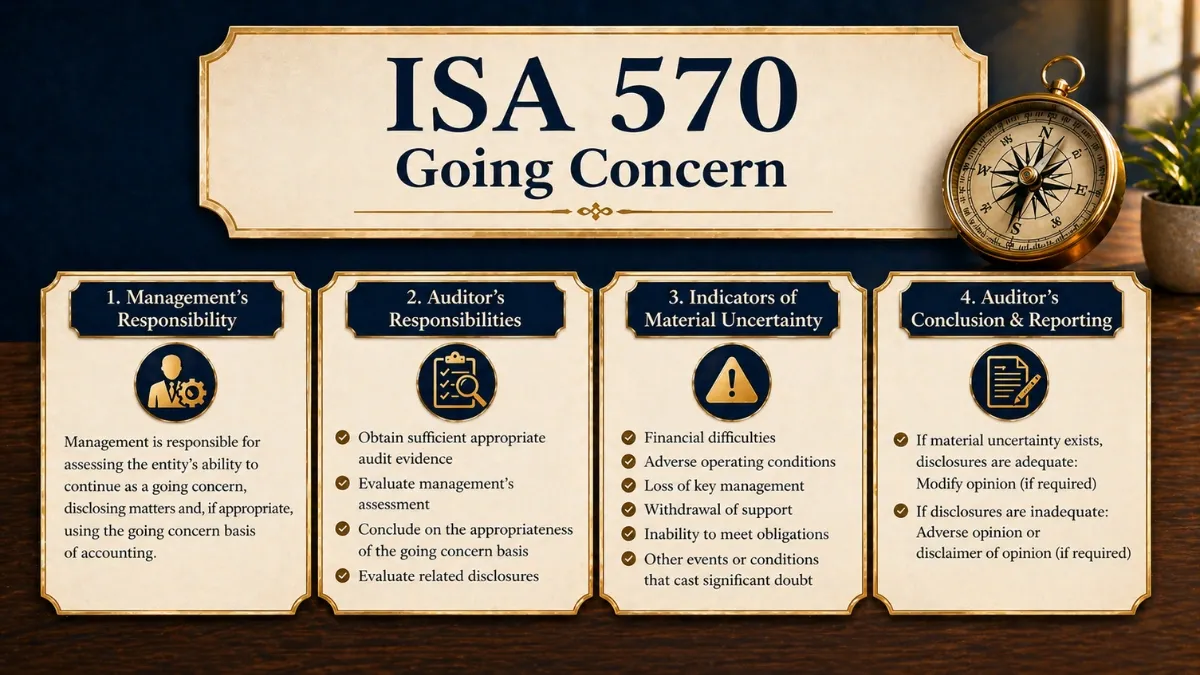
ISA 570 (Revised 2024) – Going Concern deals with the auditor’s responsibilities in the ‘audit‘ of financial statements relating to going concern and the implications for the auditor’s report. Last Updated – April, 2026 IAASB International Standard on Auditing ISA 570 – Going Concern Updated 2024 Revision 📅 Effective: December … Read More

ISA 510 – Initial Audit Engagements—Opening Balances

ISA 510

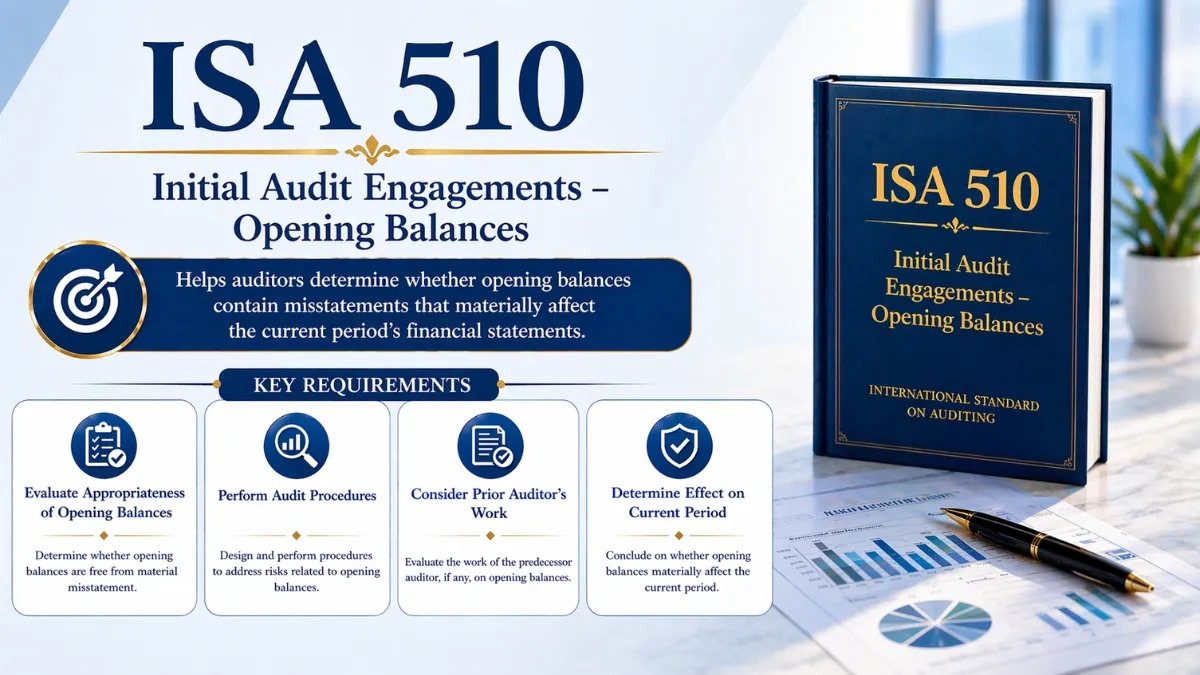
ISA 510 – Initial Audit Engagements (Opening Balances) deals with the auditor’s responsibilities relating to opening balances in an ‘initial audit engagement’. Last Updated – April, 2026 Home › Audit › ISA 510 International Standard on Auditing ISA 510 – Initial Audit Engagements: Opening Balances A comprehensive, authoritative reference for … Read More

ISA 501 – Audit Evidence—Specific Considerations for Selected Items

ISA 501

ISA 501 – Audit Evidence (Specific Considerations for Selected Items) deals with specific considerations by the auditor in obtaining sufficient appropriate audit evidence in accordance with ISA 330, ISA 500 and other relevant ISAs with respect to certain aspects of ‘Inventory‘, ‘Litigation and Claims‘ involving the entity and ‘Segment Information‘ … Read More

ISA 530 – Audit Sampling

ISA 530

ISA 530 – Audit Sampling applies when the auditor has decided to use “audit sampling” in performing audit procedures. Last Updated – April, 2026 Home › Audit › ISA 530 International Standard on Auditing ISA 530Audit Sampling A practitioner-level guide covering sample design, size determination, selection methods, projecting misstatements, and … Read More