IFRIC 19 – Extinguishing Financial Liabilities with Equity Instruments states that the derecognition of financial liabilities takes place when it is extinguished i.e. when the obligation specified in the contract is discharged or canceled or expired.
Last Updated – October, 2026
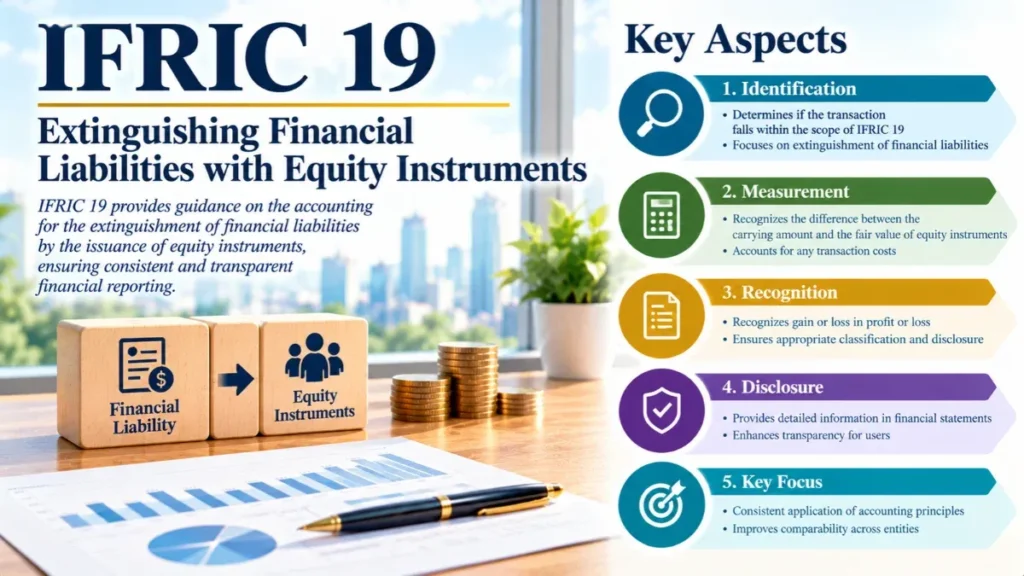
IFRIC 19 – Extinguishing Financial Liabilities with Equity Instruments
A practical guide to accounting for debt-for-equity swaps under IFRS; scope, measurement, journal entries, a worked example and the questions practitioners ask most.
Key Takeaways
- IFRIC 19 explains how a company accounts for a debt that is settled by issuing its own shares to the lender.
- The shares issued are treated as consideration paid to extinguish the liability.
- They are measured at fair value (or, if that cannot be measured reliably, the fair value of the liability settled).
- The difference between the liability’s carrying amount and the consideration paid goes to profit or loss.
What Is IFRIC 19?
IFRIC 19 Extinguishing Financial Liabilities with Equity Instruments is an interpretation issued in November 2009 and developed by the IFRS Interpretations Committee. It tells a reporting entity how to account for a debt-for-equity swap, a transaction in which a debtor and a creditor renegotiate a financial liability so that all or part of it is settled by the debtor issuing its own equity instruments.
These swaps are common when a company is under financial pressure, when a lender prefers an ownership stake to a doubtful repayment, or when a restructuring is designed to strengthen the balance sheet. The interpretation applies to annual periods beginning on or after 1 July 2010 and addresses the accounting of the debtor only, not the creditor.
When you give a creditor shares to settle a debt, you record the shares at fair value, remove the liability, and take any difference straight to profit or loss.
Why IFRIC 19 Was Introduced
Before IFRIC 19, practice varied. Some preparers argued that shares issued to settle a debt were not really “consideration paid”, so no gain or loss should be recognised. Others measured the equity at the carrying amount of the debt. The result was inconsistent reporting of identical transactions.
The Committee addressed four questions:
- Are an entity’s equity instruments “consideration paid” when extinguishing a financial liability?
- How should that equity be initially measured?
- How should the difference between the liability’s carrying amount and the equity issued be accounted for?
- How should a partial extinguishment be treated?
The answers bring debt-for-equity swaps into line with the general derecognition rules for financial liabilities in IFRS 9 (formerly IAS 39).
IFRIC 19 Scope and Exclusions
IFRIC 19 applies when a debtor extinguishes all or part of a financial liability by issuing equity instruments to the creditor. Under paragraph 3 of the interpretation, it does not apply in the following situations:
Within scope
A lender renegotiates a loan and accepts newly issued shares in full or partial settlement of the amount owed.
Shareholder as creditor
The creditor is also a direct or indirect shareholder and is acting in its capacity as an existing shareholder.
Common control
The creditor and the entity are controlled by the same party or parties before and after the transaction, and the substance includes an equity distribution by, or contribution to, the entity.
Original contractual terms
Settling the liability by issuing shares is in accordance with the original terms of the liability, for example when a conversion feature is exercised.
Where an exclusion applies, look to other IFRS requirements, such as those for compound instruments in IAS 32 or for transactions with owners.
The Core Accounting Requirements
1. Equity instruments are consideration paid
Issuing shares to the creditor is consideration paid to extinguish the liability. This brings the transaction under IFRS 9, a financial liability is removed from the statement of financial position when, and only when, it is extinguished (paragraph 3.3.1), and the difference between its carrying amount and the consideration paid is recognised in profit or loss (paragraph 3.3.3).
2. Measure the equity at fair value
The equity instruments issued are initially measured at their fair value at the date the liability (or part of it) is extinguished (IFRIC 19 paragraph 5). Only if that fair value cannot be reliably measured should the entity use the fair value of the liability extinguished instead (paragraph 7). For listed shares, a quoted price will usually be available. For unlisted entities, a valuation technique consistent with IFRS 13 is needed.
3. Recognise the difference in profit or loss
The gap between the carrying amount of the liability (or the part extinguished) and the consideration paid is a gain or loss in profit or loss. The entity presents it as a separate line item in profit or loss or discloses it in the notes (paragraph 11).
| Situation | Accounting result |
|---|---|
| Fair value of shares < carrying amount of debt | Gain in profit or loss |
| Fair value of shares = carrying amount of debt | No gain or loss |
| Fair value of shares > carrying amount of debt | Loss in profit or loss |
How to Apply IFRIC 19 Step by Step
- Confirm scope. Check that the creditor is not acting as a shareholder, that there is no common-control arrangement, and that the settlement is not simply a conversion under the original terms.
- Identify the extinguishment date. This is generally the date the equity instruments are issued and the liability is legally discharged.
- Determine the carrying amount. Use the amortised cost of the liability (including accrued interest) immediately before settlement.
- Measure the shares at fair value. Use a quoted price where available, otherwise a valuation technique. Fall back to the liability’s fair value only if the equity cannot be reliably measured.
- Derecognise the liability and record the equity. Remove the debt and recognise share capital and share premium (or the relevant equity components) at fair value.
- Recognise the gain or loss. Take the difference to profit or loss and make the required presentation or disclosure.
Worked Example with Journal Entries
Alpha Ltd has a bank loan with a carrying amount of $1,000,000, including accrued interest. Due to cash-flow difficulties, the bank agrees to accept 100,000 new ordinary shares (nominal value $1 each) in full settlement. On the settlement date, Alpha’s shares trade at $8.00 each.
| Item | Amount ($) |
|---|---|
| Carrying amount of loan extinguished | 1,000,000 |
| Fair value of equity issued (100,000 × $8.00) | (800,000) |
| Gain on extinguishment (profit or loss) | 200,000 |
| Account | Debit ($) | Credit ($) |
|---|---|---|
| Bank loan | 1,000,000 | |
| Share capital (100,000 × $1) | 100,000 | |
| Share premium | 700,000 | |
| Gain on debt extinguishment (P&L) | 200,000 | |
| Total | 1,000,000 | 1,000,000 |
If Alpha’s shares were worth $11.50 each, the equity would have a fair value of $1,150,000. Alpha would record a loss of $150,000 in profit or loss, because it gave up more value than the debt it extinguished.
Directly attributable costs of issuing the shares, such as legal and registration fees, are accounted for under IAS 32 as a deduction from equity, not as part of the gain or loss.
Partial Settlements and Debt Modifications
If shares are issued to settle only part of a liability, the entity must assess whether some of the consideration paid relates to a modification of the terms of the remaining liability. If it does, the consideration is allocated between the part extinguished and the part that remains outstanding, using all relevant facts and circumstances (paragraph 8).
The consideration allocated to the remaining liability then forms part of the assessment of whether its terms have been substantially modified. If they have, the modification is accounted for as the extinguishment of the original liability and the recognition of a new one, as required by IFRS 9 paragraph 3.3.2. In practice, preparers should document:
- which portion of the debt the shares are intended to settle,
- any change to interest rate, maturity or covenants on the remaining balance, and
- the basis for allocating the consideration between the two parts.
Common IFRIC 19 Accounting Mistakes
- Recording equity at the carrying amount of the debt. This hides the gain or loss that IFRIC 19 requires.
- Using the wrong measurement date. Fair value is determined when the liability is extinguished, not when negotiations began.
- Ignoring the scope exclusions. Swaps with controlling shareholders or under original conversion terms follow different guidance.
- Forgetting accrued interest. The carrying amount should include interest accrued up to settlement.
- Treating issue costs as an expense. Equity issue costs reduce equity under IAS 32.
- Under-documenting valuations. For unlisted shares, auditors will expect a well-supported fair value.
Frequently Asked Questions
What does IFRIC 19 deal with?
IFRIC 19 deals with how a debtor accounts for the extinguishment of a financial liability through the issue of its own equity instruments to the creditor, commonly known as a debt-for-equity swap.
When did IFRIC 19 become effective?
It applies to annual periods beginning on or after 1 July 2010, with earlier application permitted.
How are shares issued under IFRIC 19 measured?
They are measured at fair value on the extinguishment date. If that fair value cannot be reliably measured, the fair value of the liability extinguished is used.
Where is the gain or loss on a debt-for-equity swap recognised?
In profit or loss. It equals the difference between the carrying amount of the liability extinguished and the consideration paid, which is the fair value of the equity instruments issued.
Does IFRIC 19 apply to convertible bonds?
Not when the conversion happens under the original contractual terms. Those cases fall outside its scope and are dealt with under IAS 32 and IFRS 9 requirements for compound instruments.
Does IFRIC 19 apply when the lender is also a shareholder?
It does not apply if the lender is acting in its capacity as an existing shareholder. In those cases the transaction is analysed as a transaction with an owner.
What happens if only part of the debt is settled with shares?
The entity assesses whether part of the consideration relates to a modification of the remaining liability, allocates the consideration accordingly, and applies the IFRS 9 modification rules to the remaining balance.
Does IFRIC 19 cover the creditor’s accounting?
No. The interpretation addresses only the accounting by the entity that issues the equity instruments (the debtor).
Conclusion
IFRIC 19 gives finance teams a consistent, fair-value-based answer to a difficult restructuring question. By treating the shares as consideration paid, measuring them at fair value and recognising the difference in profit or loss, it ensures that debt-for-equity swaps are reported transparently and comparably across entities.
For any real transaction, confirm the scope first, document the fair value carefully, and review the presentation and disclosure requirements with your auditor.
Sources and References
- IFRIC 19 Extinguishing Financial Liabilities with Equity Instruments, IFRS Foundation (standard page and history of amendments).
- Full text of IFRIC 19, IFRS Foundation (a free IFRS Foundation registration may be required).
- IFRIC 19 summary, ICAEW.
- IFRS 9 Financial Instruments, derecognition of financial liabilities (paragraphs 3.3.1 to 3.3.3).
- IAS 32 Financial Instruments: Presentation, classification of liabilities and equity.
- IFRS 13 Fair Value Measurement, measuring the fair value of the shares issued.
Disclaimer: This article is for general educational purposes and is not accounting, tax or legal advice. IFRS requirements are subject to amendment. Always refer to the current standards and consult a qualified professional for your specific circumstances.
(Qualified) Chartered Accountant – ICAP
Master of Commerce – HEC, Pakistan
Bachelor of Accounting (Honours) – AeU, Malaysia