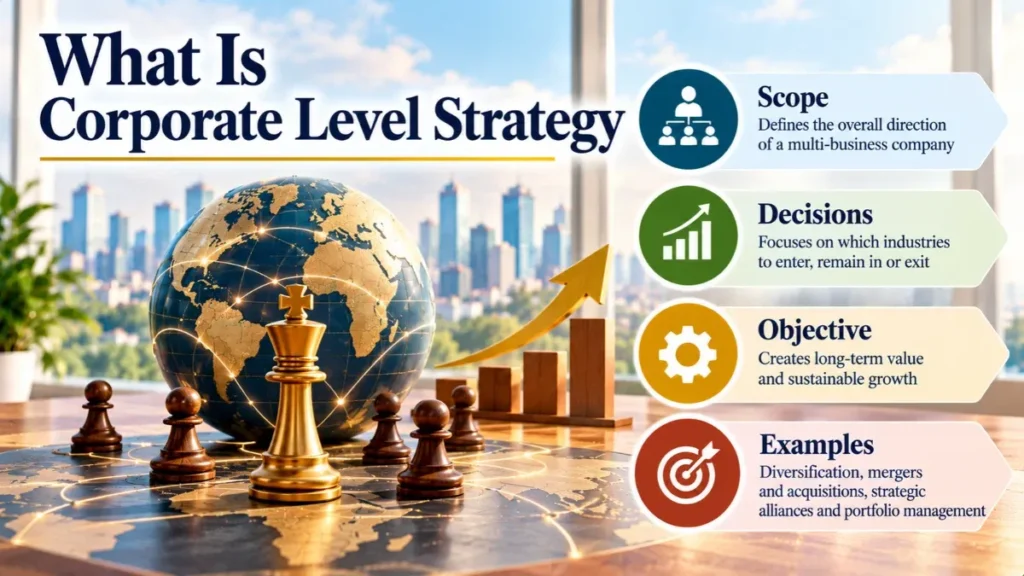
The concept what is corporate level strategy is the overarching approach that determines which industries and markets a company should operate in, how its different business units should work together, and how the organization can create long-term value.
Through established frameworks such as the BCG Growth-Share Matrix and Ansoff Matrix, businesses can evaluate strategic opportunities, allocate resources effectively, and achieve sustainable competitive advantage. This guide explores the definition, importance, frameworks, implementation methods, and real-world examples of corporate level strategy.
Last Updated – November, 2026
Strategic Management • Corporate Strategy
What Is Corporate Level Strategy?
A clear, practical guide to the plan that decides which businesses a company should be in; its types, methods, frameworks, real-world examples and the accounting implications behind it.
What Is Corporate Level Strategy?
Corporate level strategy is the overarching plan that decides which businesses a company should compete in, how those businesses fit together, and how the parent organization creates more value than they could create alone. It answers the most fundamental question in management: “What business (or businesses) should we be in?”
In practical terms, it covers decisions such as entering a new industry, acquiring a competitor or supplier, forming a joint venture, selling off a division that no longer fits, or expanding into a new country. These choices shape the long-term identity and profitability of the firm.
Key Takeaway
Corporate level strategy is about where to compete and how the whole is worth more than the sum of its parts. Business level strategy, by contrast, is about how to compete within a chosen market.
Why Is Corporate Level Strategy Important?
A company with strong individual business units can still destroy value if the portfolio is poorly assembled. A sound corporate strategy gives leadership a disciplined way to decide where to invest and where to step back. Its main benefits include:
- Sustained growth: it opens new revenue streams when existing markets mature or decline.
- Risk reduction: a balanced portfolio spreads exposure across industries, cycles, and regions.
- Synergy creation: shared technology, brands, distribution, and expertise lower costs and speed up innovation.
- Efficient capital allocation: cash generated by mature units funds promising ventures elsewhere.
- Competitive advantage: scale, bargaining power, and market reach become harder for rivals to copy.
- Clear direction: managers and investors understand the company’s purpose and priorities.
Corporate vs Business vs Functional Strategy
Strategy is usually organized in three layers. Each layer answers a different question and is owned by a different group of leaders, yet all three must stay aligned.
| Level | Core Question | Owned By | Typical Decisions |
|---|---|---|---|
| Corporate | Which businesses should we be in? | Board and top executives | Diversification, acquisitions, divestitures, portfolio balance |
| Business (Competitive) | How do we win in each market? | Business unit heads | Cost leadership, differentiation, focus, pricing, positioning |
| Functional | How do we execute day to day? | Department managers | Marketing plans, operations, HR, finance, R&D |
What Are the Main Types of Corporate Level Strategy?
Most corporate strategies fall into four broad directions, often described as grand strategies. A company may pursue different ones at different times, or even different ones for different units at the same time.
1. Growth Strategy
Expanding sales, market share, or scope through new products, new markets, mergers, or acquisitions. It is the most common choice for companies in healthy, expanding industries.
2. Stability Strategy
Maintaining the current scope and protecting existing positions. Firms choose it when markets are mature, resources are limited, or the risk of change outweighs the reward.
3. Retrenchment Strategy
Reducing operations through cost cutting, asset sales, or exits from weak businesses. It helps a company recover when performance declines or when focus is lost.
4. Combination Strategy
Blending growth, stability, and retrenchment across different business units. Large conglomerates typically do this, expanding some units while trimming others.
Related vs Unrelated Diversification
Diversification is the heart of many corporate strategies. It means entering businesses that differ from the company’s original activity. The key question is whether the new businesses share meaningful links with the old ones.
Related (Concentric) Diversification
The company moves into businesses that share technology, customers, distribution channels, or skills with its core. Because the units overlap, the firm can capture economies of scope and transfer know-how from one unit to another. A food company adding a beverage line that uses the same retail partners is a typical example.
Unrelated (Conglomerate) Diversification
The company enters industries with little operational connection to its core. The logic here is financial rather than operational: spreading risk, buying undervalued assets, and applying superior capital allocation and management oversight. This approach demands exceptional discipline at the corporate center, since there are few natural synergies to rely on.
Methods of Implementing Corporate Level Strategy
Once direction is set, leaders must choose the vehicle that will carry the strategy forward. Each route balances speed, control, cost, and risk differently.
Vertical Integration
Taking over earlier stages (backward integration) or later stages (forward integration) of the value chain to secure supply, cut costs, or control the customer experience.
Mergers and Acquisitions
The fastest way to gain new capabilities, products, or market access, though integration challenges frequently erode the expected value.
Strategic Alliances and Joint Ventures
Sharing resources and risk with partners when entering unfamiliar markets, without the full commitment of ownership.
Internal Development
Building new businesses from within, which preserves culture and control but typically takes longer than buying growth.
Divestiture and Spin-offs
Selling or separating units that no longer fit, freeing capital and management attention for stronger priorities.
International Expansion
Entering foreign markets through exports, licensing, partnerships, or direct investment to reach new customers and lower costs.
Corporate Level Strategy Frameworks and Models
Managing a multi-business company requires structured tools. Four frameworks appear most often in strategic management courses and boardrooms:
BCG Growth-Share Matrix
This classic model sorts business units into Stars, Cash Cows, Question Marks, and Dogs, based on market growth and relative market share. Cash cows generate funds that are reinvested in stars and promising question marks, while dogs are candidates for divestment.
GE–McKinsey Nine-Box Matrix
A more detailed alternative that rates each unit on industry attractiveness and competitive strength, producing nine cells that guide invest, hold, or harvest decisions.
Ansoff Matrix
This tool maps growth options by combining existing or new products with existing or new markets: market penetration, market development, product development, and diversification.
Parenting Advantage (Goold and Campbell)
Rather than asking whether a business is attractive, this lens asks whether the corporate parent is the right owner for it, meaning whether headquarters adds more value than it destroys.
Corporate Strategy and Financial Reporting Implications
Every corporate strategy decision leaves a visible footprint in the financial statements. Understanding that footprint helps leaders judge whether a strategy is truly creating value, not just growing the balance sheet. Under IFRS, the most relevant standards include:
- IFRS 3 (Business Combinations): the acquirer recognizes the identifiable assets acquired and liabilities assumed, generally at fair value. Goodwill arises when the consideration transferred, plus any non-controlling interests and any previously held interest in the acquiree, exceeds the net identifiable assets acquired.
- IAS 36 (Impairment of Assets): goodwill is tested for impairment at least annually, so an overpriced acquisition can eventually show up as a charge to profit.
- IFRS 10 (Consolidated Financial Statements): once a parent controls other entities, their results are combined into group accounts.
- IFRS 8 (Operating Segments): requires eligible entities to disclose financial information about their operating segments, helping investors understand the performance of different business activities.
- IFRS 5 (Non-current Assets Held for Sale and Discontinued Operations): establishes requirements for classifying qualifying assets and disposal groups as held for sale and presenting qualifying discontinued operations separately.
Beyond compliance, finance teams typically evaluate portfolio decisions using return on invested capital (ROIC), economic value added, and the weighted average cost of capital (WACC). A business that consistently earns less than its cost of capital is a strong candidate for restructuring or sale, regardless of how large it is.
Practical Note
Other reporting frameworks, such as US GAAP or local standards, have equivalent requirements with differences in detail. Always apply the framework that governs the reporting entity.
Real-World Examples of Corporate Level Strategy
The Walt Disney Company
Disney built its portfolio through targeted acquisitions, including Pixar, Marvel, and Lucasfilm. Each purchase added valuable intellectual property that could be monetized across films, streaming, theme parks, and merchandise, a textbook case of related diversification with strong synergies.
Alphabet Inc.
In 2015, Google reorganized under a new parent, Alphabet, separating its core search and advertising business from long-term bets in other fields. The structure lets leadership allocate capital to experimental ventures while keeping the main business accountable on its own.
Berkshire Hathaway
Berkshire is a well-known example of unrelated diversification. It owns businesses in insurance, railroads, energy, and manufacturing, and its value comes primarily from disciplined capital allocation at the corporate center rather than from operational overlap.
General Electric
Once one of the world’s most sprawling conglomerates, GE gradually narrowed its focus and ultimately separated into independent companies centered on aerospace and energy. The journey illustrates how a corporate strategy can shift from broad diversification toward focus when the parent stops adding value.
Tata Group
Tata operates across steel, automobiles, technology services, hospitality, and consumer goods, supported by a shared brand and a centralized governance approach. It shows how a conglomerate can use a trusted corporate identity to enter diverse markets.
How to Develop an Effective Corporate Level Strategy
While every organization is unique, most effective corporate strategies follow a similar process:
- Define the mission, vision, and values. Clarify the purpose of the company and the boundaries within which it will operate.
- Analyze the external environment. Study industry trends, competitors, regulation, technology shifts, and customer needs using tools such as PESTEL and Porter’s Five Forces.
- Assess internal resources and capabilities. Identify the core competencies, financial strength, and assets that could be leveraged across businesses.
- Evaluate the current portfolio. Use frameworks like the BCG or GE–McKinsey matrix, together with financial returns, to judge which units deserve investment, maintenance, or exit.
- Choose the strategic direction. Decide among growth, stability, retrenchment, or a combination, and select the appropriate diversification approach.
- Select the means of execution. Compare acquisition, alliance, and internal development in terms of speed, cost, and risk.
- Allocate resources and set governance. Assign capital, talent, and decision rights, and define the role headquarters will play.
- Monitor, measure, and adapt. Track performance with clear KPIs and revisit the strategy as conditions change.
Common Challenges and Pitfalls
Even well-intentioned strategies can fail. Leaders should watch out for the following traps:
- Over-diversification: stretching management attention across too many unrelated businesses.
- Overpaying for acquisitions: synergies are often overestimated while integration costs are underestimated.
- Cultural clashes: combining organizations with incompatible values and working styles.
- Neglecting the core: pursuing exciting new ventures while the main business loses its edge.
- Weak corporate parenting: a headquarters that adds bureaucracy rather than value.
- Slow response to change: holding onto declining units for emotional or political reasons.
Frequently Asked Questions
What is corporate level strategy in simple words?
It is the top-level plan that decides which businesses a company should own or operate and how they should work together to create more value than they would separately.
What is the difference between corporate and business level strategy?
Corporate level strategy determines which industries and markets the company competes in. Business level strategy determines how a single unit competes within its market, for example through low cost or differentiation.
Who is responsible for corporate level strategy?
The board of directors, the CEO, and the senior executive team are primarily responsible, often supported by corporate strategy and finance departments.
What are the four main types of corporate level strategy?
Growth, stability, retrenchment, and combination strategies. Growth expands the company, stability maintains it, retrenchment shrinks or refocuses it, and combination mixes the other three.
Why is diversification part of corporate strategy?
Diversification lets a company reduce dependence on a single market, find new growth opportunities, and apply its strengths in additional industries. It should only be pursued when it creates real value for the parent.
Which tools help with corporate level strategy decisions?
Common tools include the BCG growth-share matrix, the GE–McKinsey nine-box matrix, the Ansoff matrix, SWOT analysis, PESTEL analysis, and the parenting advantage framework.
How does corporate level strategy affect a company’s financial statements?
Acquisitions can create goodwill that must be tested for impairment, group structures require consolidation, eligible entities disclose operating segment information, and qualifying disposals are classified as held for sale or presented as discontinued operations under IFRS.
Final Thoughts
Corporate level strategy sets the stage for everything that follows in an organization. By choosing the right mix of businesses, the right methods of growth, and the right role for headquarters, leaders build a company that is more resilient, more profitable, and more valuable than a collection of separate units.
Whether you are a student of strategic management, a manager planning your next move, or an entrepreneur thinking about expansion, the central question stays the same: does each business in the portfolio belong here, and does the whole create more value than the parts? Answer that honestly, and the rest of your strategy becomes far clearer.
References and Further Reading
- Ansoff, H. I. (1957). “Strategies for Diversification.” Harvard Business Review, 35(5), 113–124. September 1957 issue contents.
- Porter, M. E. (1987). “From Competitive Advantage to Corporate Strategy.” Harvard Business Review, 65(3), 43–59.
- Goold, M., Campbell, A., & Alexander, M. (1994). Corporate-Level Strategy: Creating Value in the Multibusiness Company. John Wiley & Sons.
- Rumelt, R. P. (1982). “Diversification Strategy and Profitability.” Strategic Management Journal, 3(4), 359–369.
- IFRS Foundation. Official standards pages: IFRS 3 Business Combinations, IFRS 5 Non-current Assets Held for Sale and Discontinued Operations, IFRS 8 Operating Segments, IFRS 10 Consolidated Financial Statements and IAS 36 Impairment of Assets.
This article is provided for general educational purposes and does not constitute professional accounting, tax, legal, or investment advice. Consult a qualified professional before making decisions based on its content.
(Qualified) Chartered Accountant – ICAP
Master of Commerce – HEC, Pakistan
Bachelor of Accounting (Honours) – AeU, Malaysia